Impact Assessment of US/Israel-Iran Conflict
Impact Assessment of US/Israel-Iran Conflict
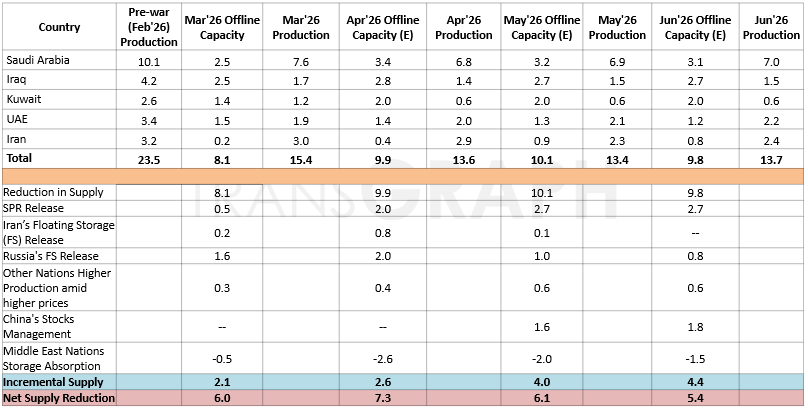
- Qatar is seeking to broker a US-Iran peace deal to end the eight-month war and reopen the Strait of Hormuz, despite Trump rejecting reports of sanctions relief, while the conflict continues to disrupt oil supplies and drive global energy prices higher.
- Middle East crude exports rose to 16.328 Mbpd in Sep’26, the highest since the war began in late Feb’26, with Saudi Arabia’s exports rebounding to about 5.4 Mbpd from 2.446 Mbpd in Aug’26 as Strait of Hormuz flows recovered to around 9.719 Mbpd.
- Despite the rebound, regional exports remained 3.2 Mbpd below February’s 19.513 Mbpd, at just under 80% of pre-conflict levels, while 19 VLCCs carrying about 2 Mbpd each of Saudi crude crossed the Strait of Hormuz last week.
- Indian refiners expect Russian crude supplies to tighten further in Oct’26–Nov’26 as Chinese demand outbids India, with Russian oil arrivals already falling 16.5% to 2.1 MBpd in Aug’26 and projected to decline to around 1.75 MBpd in Sep’26, prompting India to seek costlier alternatives such as UAE Murban, Iraqi Basrah and Angolan crude.
- Crude oil flows through the Strait of Hormuz totaled 33.7 mln bbl in the week ending 25th Sep’26, with 19 tankers including, 17 VLCCs, keeping exports broadly in line with the previous week’s 49.2 mln bbl.
- Libya’s National Oil Corporation said on Saturday that it had reopened Valve No. 7 on the main Sharara–Zawiya crude pipeline, allowing pumping operations to resume.
- Crude flows are gradually returning to normal after the pipeline was shut earlier last week, with the Sharara field’s output capacity of around 0.30 MBpd expected to progressively come back online.
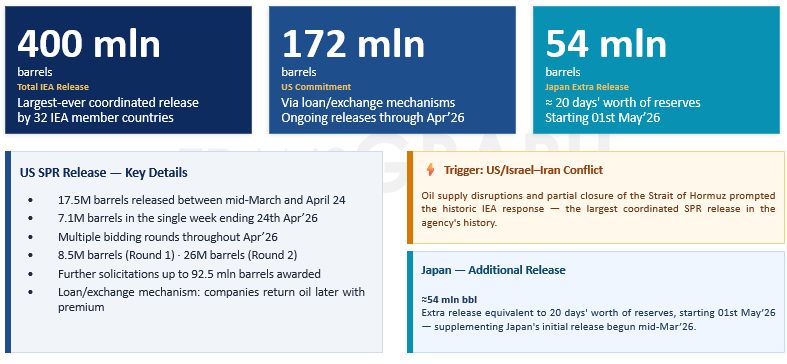
- The US government is offering energy companies up to 40 mln bbl of crude from the Strategic Petroleum Reserve, following a broader 400 mln bbl global reserve release involving about 30 IEA countries, with the US initially committed to 172 mln bbl.
- The latest offer comes as US SPR stocks have fallen below 284 mln bbl, while gasoline prices have risen nearly 50% to about 4.45 USD/gallon and diesel prices have surged around 70% to roughly $6.50 USD/gallon since the Iran war began.
- The White House is urging EU countries to release more emergency diesel and oil reserves to ease surging fuel prices ahead of the US midterm elections, while considering additional measures to boost domestic diesel supplies.
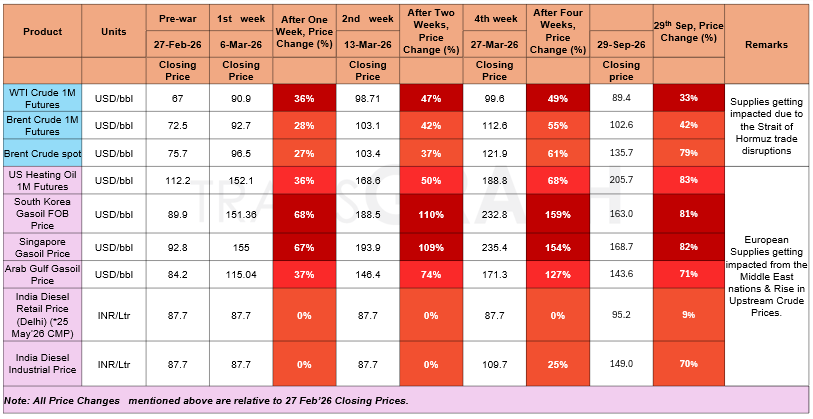
War Impact on Crude Oil & Gasoil/Diesel Prices
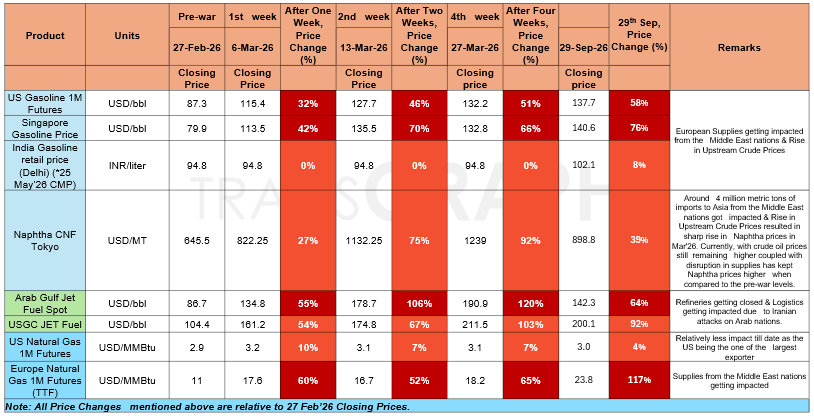
War Impact on Gasoline, ATF & Natural Gas Prices
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
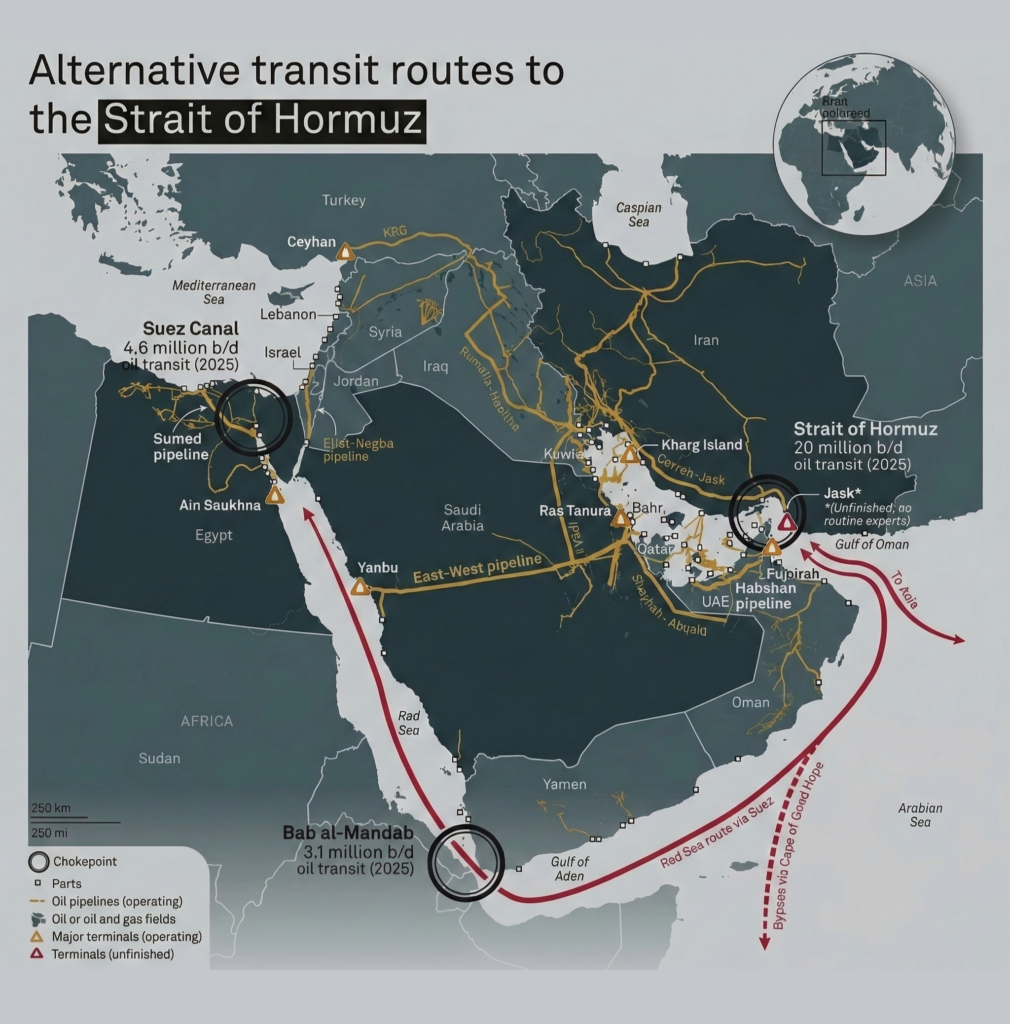
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
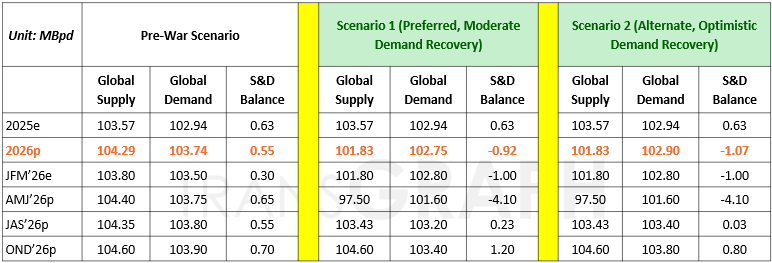
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
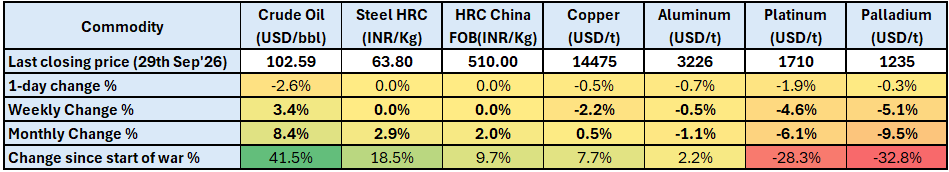
War Front: President Trump has indicated that US has rejected the latest peace deal. Fears of fresh attacks have risen amid breakdown in negotiations weighing on base metals. US President Donald Trump has rejected a news report claiming his administration offered Iran sanctions relief and access to frozen funds, calling the story a hoax on social media. Iranian Foreign Minister Abbas Araghchi says Tehran has held further indirect talks with the United States through Qatari mediators in New York, with Washington’s formal response expected by Tuesday.
The United States and China have agreed to reduce tariffs on $30 billion of goods and launch a dialogue on AI, both countries said following President Xi Jinping's visit to Washington. The tariff reductions would apply to US exports such as agricultural goods, wood and cosmetics, as well as US imports including small appliances, toys, decorations, a White House statement said on Friday.
Recently New York Fed President John Williams said there was “no urgency” to raise rates again. This reduced expectations of an immediate/October Fed hike: Saudi Arabia restarted flows through its East-West pipeline after repairs following drone attacks. September crude exports from Middle Eastern producers reached about 16.3 million barrels/day. The US offered to loan up to 40 million barrels from its Strategic Petroleum Reserve. This adds another potential source of crude supply and therefore put downward pressure on prices. These factors eased near-term supply concerns, reducing inflation pressure.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 2.9% on a monthly basis due to raw material price surge and stronger demand from auto sector.
Base metals:
- LME 3M copper are down 2.2% on a weekly basis as mid autumn festival slowed China consumption. Further, rejection of peace deal by US and stronger dollar is weighing on metals. However, high premiums and supply disruptions will provide some support.
- Aluminum prices are down 1.1% due to gradual recovery from GCC and stronger dollar despite tensions in the middle east.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For August 2026, Saudi Aramco Contract Prices (CPs) rebounded to USD 620/ton for propane and USD 640/ton for butane, compared with USD 580/ton and USD 600/ton, respectively, in July. This represents a 6.9% month-on-month increase in propane CPs and a 6.7% month-on-month increase in butane CPs.
- Sonatrach raised its August propane OSP by 4.2% m-o-m, from $518/ton to $540/ton, while the butane OSP was cut by 5.0%, from $600/ton to $570/ton.
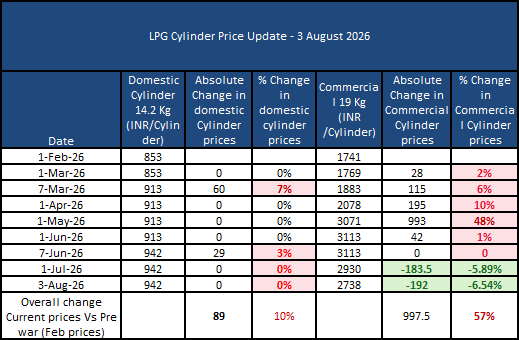
- India’s commercial LPG prices eased further in August, with the 19 kg cylinder price in New Delhi declining by ₹192, from ₹2,930 in July to ₹2,738 as of 3 August 2026. Despite the recent correction, commercial LPG remains substantially above its pre-war level of ₹1,741/cylinder. In contrast, the 14.2 kg domestic LPG cylinder remained unchanged at ₹942, reflecting continued price stability for household consumers.
Impact Assessment of US/Israel-Iran Conflict
- On 26th Sep’26, Trump said he rejected Iran’s proposal to reopen the Strait of Hormuz and halt regional fighting within seven days, while leaving the door open for further negotiations.
- Market grapevine indicates that Saudi Aramco is considering discounts of around 9 USD/bbl on its official selling prices for crude loaded off Oman, where Asian buyers have recently paid 10–20 USD/bbl premiums, as it seeks to offset record freight costs and regain market share amid disruptions to Strait of Hormuz shipments, with Saudi exports through the strait projected at 7.4 MBpd this month.
- Market grapevine indicates that crude exports from major Middle Eastern producers rose to 12.8 MBpd in Sep’26, the highest level since February, supported by increased shipments from Saudi Arabia and the UAE.
- Indian refiners expect Russian crude supplies to tighten further in Oct’26–Nov’26 as Chinese demand outbids India, with Russian oil arrivals already falling 16.5% to 2.1 MBpd in Aug’26 and projected to decline to around 1.75 MBpd in Sep’26, prompting India to seek costlier alternatives such as UAE Murban, Iraqi Basrah and Angolan crude.
- Ship-to-ship transfers off Oman have reached capacity as Saudi Arabia redirected more crude through the Strait of Hormuz, with Saudi exports via Hormuz expected to rise to 3.6 MBpd in Sep’26 from 0.9 MBpd in Aug’26, increasing tanker demand and causing congestion.
- Crude oil flows through the Strait of Hormuz totaled 33.7 mln bbl in the week ending 25th Sep’26, with 19 tankers including, 17 VLCCs, keeping exports broadly in line with the previous week’s 49.2 mln bbl.
- On 24th Sep’26, commodity-vessel transits fell to 9 from 14 a day earlier and remained well below the 10-day average of 18, while the strait typically handled around 125 large commercial vessels daily before the Iran war.
- Libya’s National Oil Corporation said on Saturday that it had reopened Valve No. 7 on the main Sharara–Zawiya crude pipeline, allowing pumping operations to resume.
- Crude flows are gradually returning to normal after the pipeline was shut earlier last week, with the Sharara field’s output capacity of around 0.30 MBpd expected to progressively come back online.
- On 28th Sep’26 Russian President Putin signed a decree further restricting the disclosure of Russian energy and oil trade data, including information on prices, buyers, sellers, routes and destinations, to make Western sanctions harder to enforce.
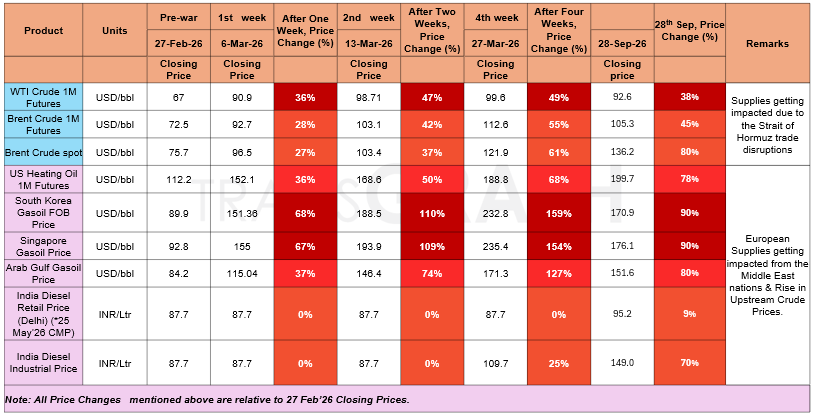
War Impact on Crude Oil & Gasoil/Diesel Prices
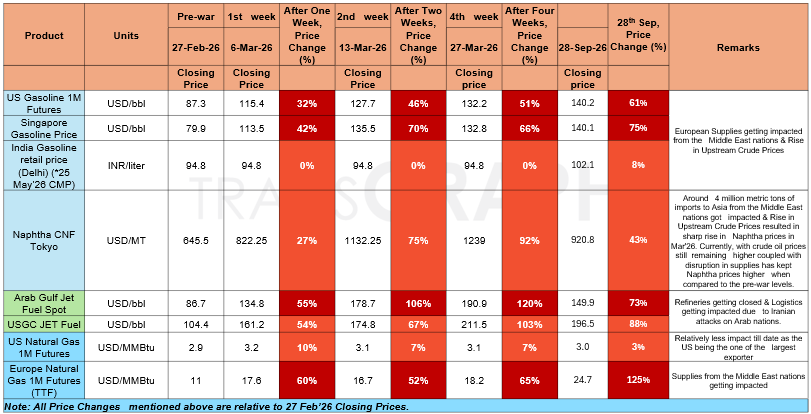
War Impact on Gasoline, ATF & Natural Gas Prices
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
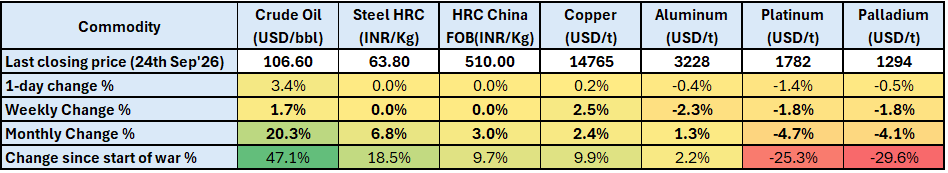
War Front: U.S.–Iran Talks Raise Hopes of De-escalation and Ease Oil Prices: U.S. and Iranian officials held around three hours of talks on the sidelines of the UN General Assembly in New York, with President Trump describing the discussions as “very good” and productive and indicating that another meeting could take place soon. The talks, mediated through regional officials, focused on conditions for ending the conflict and potentially reopening the Strait of Hormuz. The renewed diplomatic engagement, together with the restart of Saudi Arabia’s East-West oil pipeline and expectations of improving Gulf supply, has eased concerns over a prolonged disruption to energy flows, with Brent crude falling below USD 100/bbl and extending its recent decline.
The U.S Federal Reserve raised its benchmark interest rate by 25 bps to 3.75%-4.00%, marking its first rate hike since July 2023. The decision came amid persistent inflationary pressures, with the Fed stating that inflation remains elevated and that the latest rate increase would support a more timely return toward its 2% inflation target. The Fed’s updated projections indicate that 16 of 18 policymakers expect at least one more 25-bps rate hike by the end of 2026, taking the policy rate to 4.00%-4.25%. Policymakers also raised their 2026 inflation forecast, reflecting continued concerns over price pressures, particularly from higher energy costs. The Fed’s hawkish stance provides a positive backdrop for the USD and weigh on metal prices. This may keep the impact on INR relatively contained, with oil prices, capital flows and RBI intervention remaining key drivers.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 6.8% on a monthly basis due to raw material price surge.
Base metals:
- LME 3M copper are up 2.5% on a weekly basis supported by high China premium, disruptions in Escondida mine, calls for strike at major Chile mining operations, and drawdown in SHFE inventory ahead of mid autumn festival. However upside remains capped by rate hike pressures, stronger dollar, and geopolitical tensions.
- Aluminum prices are down 2.3% due to gradual recovery from GCC and rate hike expectations despite tensions in the middle east.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For August 2026, Saudi Aramco Contract Prices (CPs) rebounded to USD 620/ton for propane and USD 640/ton for butane, compared with USD 580/ton and USD 600/ton, respectively, in July. This represents a 6.9% month-on-month increase in propane CPs and a 6.7% month-on-month increase in butane CPs.
- Sonatrach raised its August propane OSP by 4.2% m-o-m, from $518/ton to $540/ton, while the butane OSP was cut by 5.0%, from $600/ton to $570/ton.
- India’s commercial LPG prices eased further in August, with the 19 kg cylinder price in New Delhi declining by ₹192, from ₹2,930 in July to ₹2,738 as of 3 August 2026. Despite the recent correction, commercial LPG remains substantially above its pre-war level of ₹1,741/cylinder. In contrast, the 14.2 kg domestic LPG cylinder remained unchanged at ₹942, reflecting continued price stability for household consumers.
Impact Assessment of US/Israel-Iran Conflict
- On 26th Sep’26, Trump said he rejected Iran’s proposal to reopen the Strait of Hormuz and halt regional fighting within seven days, while leaving the door open for further negotiations.
- Saudi Arabia intercepted six ballistic missiles launched by the Houthis toward Taif and the Yanbu area on 24th Sep’26, with the Houthis claiming attacks targeting Riyadh and Saudi Aramco facilities in Yanbu. The strikes raised concerns over the security of Saudi oil infrastructure and crude export flows through Yanbu.
- War risk insurance premiums for tankers loading at Saudi Arabia’s Yanbu port surged to around 3% of vessel value, up from below 1% in early Jul’26, as reported on 25th Sep’26, amid heightened Houthi attacks and security risks in the Red Sea.
- Ship-to-ship transfers off Oman have reached capacity as Saudi Arabia redirected more crude through the Strait of Hormuz, with Saudi exports via Hormuz expected to rise to 3.6 MBpd in Sep’26 from 0.9 MBpd in Aug’26, increasing tanker demand and causing congestion.
- Crude oil flows through the Strait of Hormuz totaled 33.7 mln bbl in the week ending 25th Sep’26, with 19 tankers including, 17 VLCCs, keeping exports broadly in line with the previous week’s 49.2 mln bbl.
- On 24th Sep’26, commodity-vessel transits fell to 9 from 14 a day earlier and remained well below the 10-day average of 18, while the strait typically handled around 125 large commercial vessels daily before the Iran war.
- Libya’s National Oil Corporation said on Saturday that it had reopened Valve No. 7 on the main Sharara–Zawiya crude pipeline, allowing pumping operations to resume.
- Crude flows are gradually returning to normal after the pipeline was shut earlier last week, with the Sharara field’s output capacity of around 0.30 MBpd expected to progressively come back online.
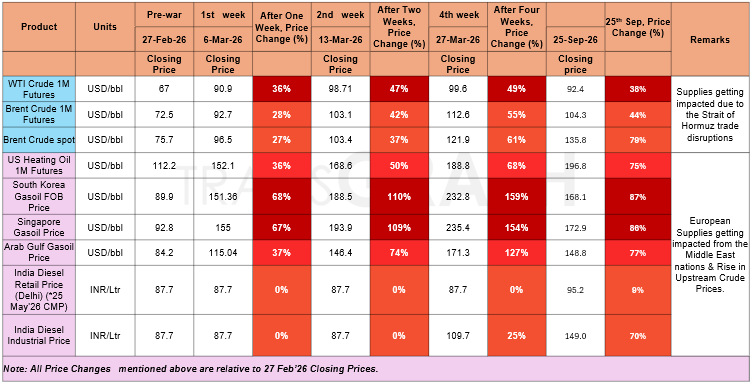
War Impact on Crude Oil & Gasoil/Diesel Prices
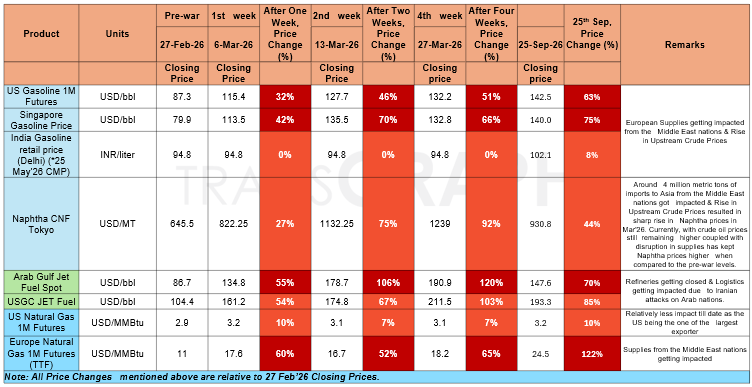
War Impact on Gasoline, ATF & Natural Gas Prices
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
War Front: U.S.–Iran Talks Raise Hopes of De-escalation and Ease Oil Prices: U.S. and Iranian officials held around three hours of talks on the sidelines of the UN General Assembly in New York, with President Trump describing the discussions as “very good” and productive and indicating that another meeting could take place soon. The talks, mediated through regional officials, focused on conditions for ending the conflict and potentially reopening the Strait of Hormuz. The renewed diplomatic engagement, together with the restart of Saudi Arabia’s East-West oil pipeline and expectations of improving Gulf supply, has eased concerns over a prolonged disruption to energy flows, with Brent crude falling below USD 100/bbl and extending its recent decline.
The U.S Federal Reserve raised its benchmark interest rate by 25 bps to 3.75%-4.00%, marking its first rate hike since July 2023. The decision came amid persistent inflationary pressures, with the Fed stating that inflation remains elevated and that the latest rate increase would support a more timely return toward its 2% inflation target. The Fed’s updated projections indicate that 16 of 18 policymakers expect at least one more 25-bps rate hike by the end of 2026, taking the policy rate to 4.00%-4.25%. Policymakers also raised their 2026 inflation forecast, reflecting continued concerns over price pressures, particularly from higher energy costs. The Fed’s hawkish stance provides a positive backdrop for the USD and weigh on metal prices. This may keep the impact on INR relatively contained, with oil prices, capital flows and RBI intervention remaining key drivers.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 6.8% on a monthly basis due to raw material price surge.
Base metals:
- LME 3M copper are up 2.5% on a weekly basis supported by high China premium, disruptions in Escondida mine, calls for strike at major Chile mining operations, and drawdown in SHFE inventory ahead of mid autumn festival. However upside remains capped by rate hike pressures, stronger dollar, and geopolitical tensions.
- Aluminum prices are down 2.3% due to gradual recovery from GCC and rate hike expectations despite tensions in the middle east.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For August 2026, Saudi Aramco Contract Prices (CPs) rebounded to USD 620/ton for propane and USD 640/ton for butane, compared with USD 580/ton and USD 600/ton, respectively, in July. This represents a 6.9% month-on-month increase in propane CPs and a 6.7% month-on-month increase in butane CPs.
- Sonatrach raised its August propane OSP by 4.2% m-o-m, from $518/ton to $540/ton, while the butane OSP was cut by 5.0%, from $600/ton to $570/ton.
- India’s commercial LPG prices eased further in August, with the 19 kg cylinder price in New Delhi declining by ₹192, from ₹2,930 in July to ₹2,738 as of 3 August 2026. Despite the recent correction, commercial LPG remains substantially above its pre-war level of ₹1,741/cylinder. In contrast, the 14.2 kg domestic LPG cylinder remained unchanged at ₹942, reflecting continued price stability for household consumers.
Impact Assessment of US/Israel-Iran Conflict
- Iranian officials say diplomacy is continuing as both sides review proposals involving the Strait of Hormuz, sanctions, and the US naval blockade.
- Market grapevine indicates that Asia’s crude oil imports are projected to reach 23.96 MBpd in Sep’26, up from 23.38 MBpd in Aug’26 and the highest since Feb’26, but still 13% below the pre-conflict average of 27.55 MBpd, Middle East supplies rose to 12.56 MBpd from 11.66 million bpd, yet remained 3.53 MBpd below the pre-war average.
- Asian imports of light and middle distillates are expected at 5.84 MBpd in Sep’26, up from 5.25 MBpd in Aug’26 but more than 1 MBpd below the pre-conflict average of 7.06 MBpd, keeping refined-fuel prices elevated.
- Saudi Arabia restarted its East-West Pipeline at a low rate after drone attacks forced its shutdown on 11th Sep’26, with plans to restore flows toward 4 MBpd (against 7 MBpd capacity) and potentially resume Yanbu exports, although a full restart could take 6–8 weeks.
- South Korea plans to reduce its reliance on Middle Eastern crude to 50% by 2035 from 70% in 2025, while adding 20 mln bbl to crude reserves by 2030, cutting Middle Eastern natural-gas dependence below 30%, and diversifying critical-mineral and naphtha supplies after disruptions from the Iran war.
- Global crude oil floating inventories declining in Sep’26 from the previous month, indicating some easing in offshore stock accumulation after the sharp build-up seen earlier in the year.
- floating crude oil storage declined across Asia, Europe, the Middle East and North Sea, likely reflecting stronger crude movements and reduced volumes held offshore. Meanwhile, West Africa and other regions saw an increase, indicating higher export-related inventories or slower cargo movements, while the Gulf Coast remained broadly stable.
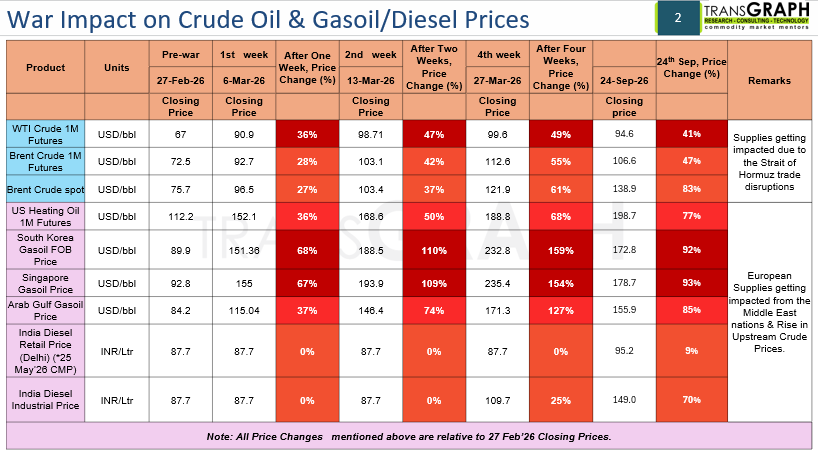
War Impact on Crude Oil & Gasoil/Diesel Prices
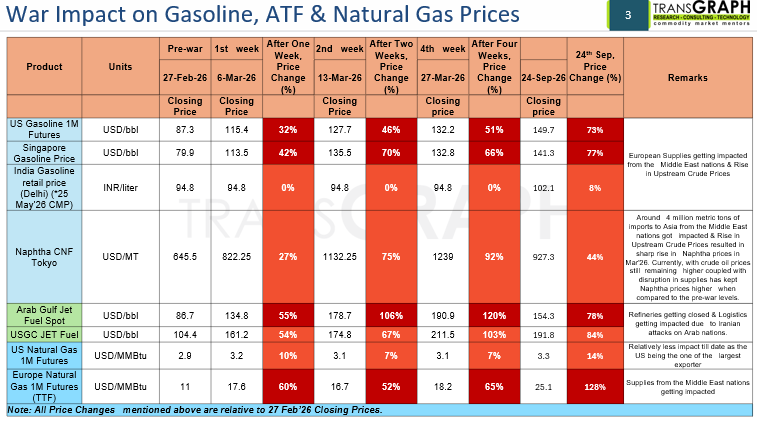
War Impact on Gasoline, ATF & Natural Gas Prices
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
War Front: U.S.–Iran Talks Raise Hopes of De-escalation and Ease Oil Prices: U.S. and Iranian officials held around three hours of talks on the sidelines of the UN General Assembly in New York, with President Trump describing the discussions as “very good” and productive and indicating that another meeting could take place soon. The talks, mediated through regional officials, focused on conditions for ending the conflict and potentially reopening the Strait of Hormuz. The renewed diplomatic engagement, together with the restart of Saudi Arabia’s East-West oil pipeline and expectations of improving Gulf supply, has eased concerns over a prolonged disruption to energy flows, with Brent crude falling below USD 100/bbl and extending its recent decline.
The U.S Federal Reserve raised its benchmark interest rate by 25 bps to 3.75%-4.00%, marking its first rate hike since July 2023. The decision came amid persistent inflationary pressures, with the Fed stating that inflation remains elevated and that the latest rate increase would support a more timely return toward its 2% inflation target. The Fed’s updated projections indicate that 16 of 18 policymakers expect at least one more 25-bps rate hike by the end of 2026, taking the policy rate to 4.00%-4.25%. Policymakers also raised their 2026 inflation forecast, reflecting continued concerns over price pressures, particularly from higher energy costs. The Fed’s hawkish stance provides a positive backdrop for the USD and weigh on metal prices. This may keep the impact on INR relatively contained, with oil prices, capital flows and RBI intervention remaining key drivers.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 6.8% on a monthly basis due to raw material price surge.
Base metals:
- LME 3M copper are up 2.5% on a weekly basis supported by high China premium, disruptions in Escondida mine, calls for strike at major Chile mining operations, and drawdown in SHFE inventory ahead of mid autumn festival. However upside remains capped by rate hike pressures, stronger dollar, and geopolitical tensions.
- Aluminum prices are down 2.3% due to gradual recovery from GCC and rate hike expectations despite tensions in the middle east.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For August 2026, Saudi Aramco Contract Prices (CPs) rebounded to USD 620/ton for propane and USD 640/ton for butane, compared with USD 580/ton and USD 600/ton, respectively, in July. This represents a 6.9% month-on-month increase in propane CPs and a 6.7% month-on-month increase in butane CPs.
- Sonatrach raised its August propane OSP by 4.2% m-o-m, from $518/ton to $540/ton, while the butane OSP was cut by 5.0%, from $600/ton to $570/ton.
- India’s commercial LPG prices eased further in August, with the 19 kg cylinder price in New Delhi declining by ₹192, from ₹2,930 in July to ₹2,738 as of 3 August 2026. Despite the recent correction, commercial LPG remains substantially above its pre-war level of ₹1,741/cylinder. In contrast, the 14.2 kg domestic LPG cylinder remained unchanged at ₹942, reflecting continued price stability for household consumers.
Impact Assessment of US/Israel-Iran Conflict
- Iranian officials say diplomacy is continuing as both sides review proposals involving the Strait of Hormuz, sanctions, and the US naval blockade.
- Market grapevine indicates that Asia’s crude oil imports are projected to reach 23.96 MBpd in Sep’26, up from 23.38 MBpd in Aug’26 and the highest since Feb’26, but still 13% below the pre-conflict average of 27.55 MBpd, Middle East supplies rose to 12.56 MBpd from 11.66 million bpd, yet remained 3.53 MBpd below the pre-war average.
- Asian imports of light and middle distillates are expected at 5.84 MBpd in Sep’26, up from 5.25 MBpd in Aug’26 but more than 1 MBpd below the pre-conflict average of 7.06 MBpd, keeping refined-fuel prices elevated.
- Saudi Arabia restarted its East-West Pipeline at a low rate after drone attacks forced its shutdown on 11th Sep’26, with plans to restore flows toward 4 MBpd (against 7 MBpd capacity) and potentially resume Yanbu exports, although a full restart could take 6–8 weeks.
- South Korea plans to reduce its reliance on Middle Eastern crude to 50% by 2035 from 70% in 2025, while adding 20 mln bbl to crude reserves by 2030, cutting Middle Eastern natural-gas dependence below 30%, and diversifying critical-mineral and naphtha supplies after disruptions from the Iran war.
- Global crude oil floating inventories declining in Sep’26 from the previous month, indicating some easing in offshore stock accumulation after the sharp build-up seen earlier in the year.
- floating crude oil storage declined across Asia, Europe, the Middle East and North Sea, likely reflecting stronger crude movements and reduced volumes held offshore. Meanwhile, West Africa and other regions saw an increase, indicating higher export-related inventories or slower cargo movements, while the Gulf Coast remained broadly stable.
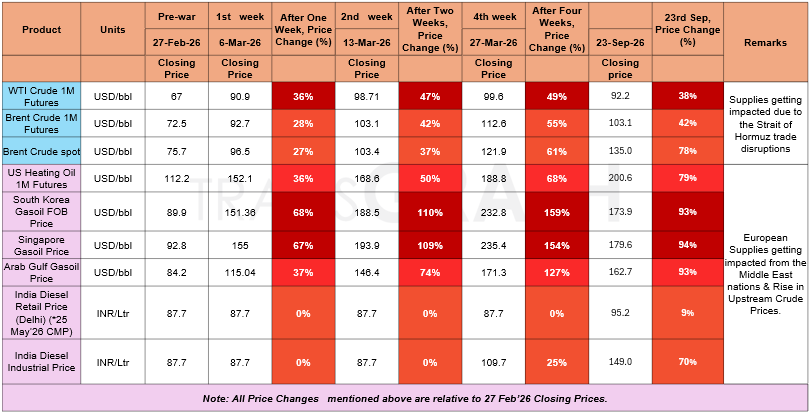
War Impact on Crude Oil & Gasoil/Diesel Prices
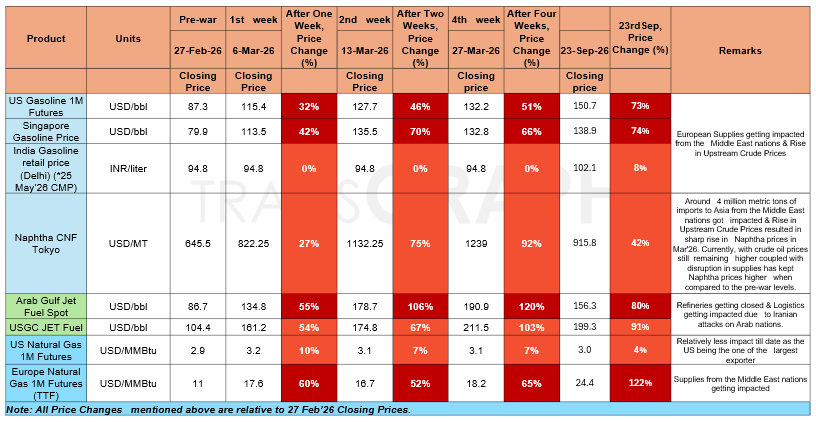
War Impact on Gasoline, ATF & Natural Gas Prices
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
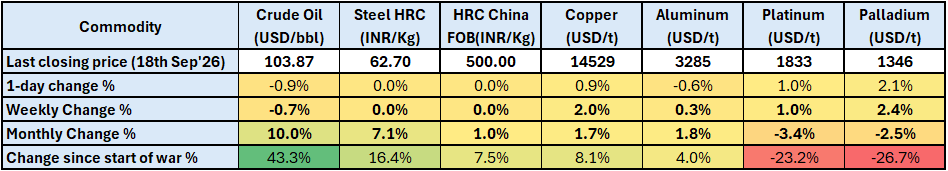
War Front: Escalation Spreads to Saudi Arabia and Red Sea.
The war continued to widen as Houthi attacks on Saudi Arabia triggered further Saudi airstrikes in Yemen and expanded security alerts across the kingdom, including near Mecca, while shipping through the Strait of Hormuz fell to just four vessels on Tuesday. The disruption to Hormuz and Saudi oil infrastructure is keeping energy markets tight, with Brent above USD 107/bbl, increasing geopolitical risk premiums and raising energy and logistics risks for GCC aluminum smelters. although crude oil prices eased on Wednesday after a larger-than-expected build in U.S. crude inventories.
The U.S Federal Reserve raised its benchmark interest rate by 25 bps to 3.75%-4.00%, marking its first rate hike since July 2023. The decision came amid persistent inflationary pressures, with the Fed stating that inflation remains elevated and that the latest rate increase would support a more timely return toward its 2% inflation target. The Fed’s updated projections indicate that 16 of 18 policymakers expect at least one more 25-bps rate hike by the end of 2026, taking the policy rate to 4.00%-4.25%. Policymakers also raised their 2026 inflation forecast, reflecting continued concerns over price pressures, particularly from higher energy costs. The Fed’s hawkish stance provides a positive backdrop for the USD and weigh on metal prices. This may keep the impact on INR relatively contained, with oil prices, capital flows and RBI intervention remaining key drivers.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 7.1% on a monthly basis due to raw material price surge.
Base metals:
- LME 3M copper are up 2% on a weekly basis supported by high China premium, and drawdown in SHFE inventory. However upside remains capped by rate hike pressures, tariff clarity, and geopolitical tensions.
- Aluminum prices are up 0.3% due to renewed tensions supporting energy prices and risk premium. However, gradual recovery from GCC and rate hike expectations will cap any significant upside.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For August 2026, Saudi Aramco Contract Prices (CPs) rebounded to USD 620/ton for propane and USD 640/ton for butane, compared with USD 580/ton and USD 600/ton, respectively, in July. This represents a 6.9% month-on-month increase in propane CPs and a 6.7% month-on-month increase in butane CPs.
- Sonatrach raised its August propane OSP by 4.2% m-o-m, from $518/ton to $540/ton, while the butane OSP was cut by 5.0%, from $600/ton to $570/ton.
- India’s commercial LPG prices eased further in August, with the 19 kg cylinder price in New Delhi declining by ₹192, from ₹2,930 in July to ₹2,738 as of 3 August 2026. Despite the recent correction, commercial LPG remains substantially above its pre-war level of ₹1,741/cylinder. In contrast, the 14.2 kg domestic LPG cylinder remained unchanged at ₹942, reflecting continued price stability for household consumers.
Impact Assessment of US/Israel-Iran Conflict
- Market grapevine indicates that Asia’s crude oil imports are projected to reach 23.96 MBpd in Sep’26, up from 23.38 MBpd in Aug’26 and the highest since Feb’26, but still 13% below the pre-conflict average of 27.55 MBpd, Middle East supplies rose to 12.56 MBpd from 11.66 million bpd, yet remained 3.53 MBpd below the pre-war average.
- Asian imports of light and middle distillates are expected at 5.84 MBpd in Sep’26, up from 5.25 MBpd in Aug’26 but more than 1 MBpd below the pre-conflict average of 7.06 MBpd, keeping refined-fuel prices elevated.
- Saudi Arabia restarted its East-West Pipeline at a low rate after drone attacks forced its shutdown on 11th Sep’26, with plans to restore flows toward 4 MBpd (against 7 MBpd capacity) and potentially resume Yanbu exports, although a full restart could take 6–8 weeks.
- Russia’s ESPO Blend crude rose above 120 USD/bbl, supported by stronger Chinese demand amid Middle East supply disruptions, while record premiums to Brent and potential US tariffs on Russian oil further tightened the market and raised global oil prices.
- South Korea plans to reduce its reliance on Middle Eastern crude to 50% by 2035 from 70% in 2025, while adding 20 mln bbl to crude reserves by 2030, cutting Middle Eastern natural-gas dependence below 30%, and diversifying critical-mineral and naphtha supplies after disruptions from the Iran war.
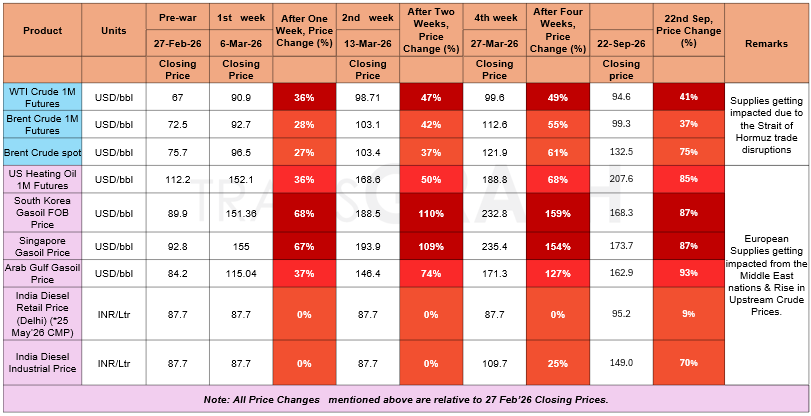
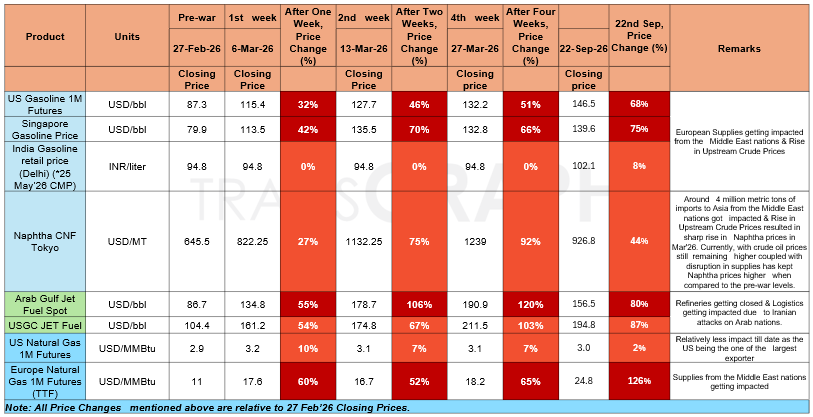
War Impact on Crude Oil & Gasoil/Diesel Prices
War Impact on Gasoline, ATF & Natural Gas Prices
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
War Front: Escalation Spreads to Saudi Arabia and Red Sea.
The war continued to widen as Houthi attacks on Saudi Arabia triggered further Saudi airstrikes in Yemen and expanded security alerts across the kingdom, including near Mecca, while shipping through the Strait of Hormuz fell to just four vessels on Tuesday. The disruption to Hormuz and Saudi oil infrastructure is keeping energy markets tight, with Brent above USD 107/bbl, increasing geopolitical risk premiums and raising energy and logistics risks for GCC aluminum smelters. although crude oil prices eased on Wednesday after a larger-than-expected build in U.S. crude inventories.
The U.S Federal Reserve raised its benchmark interest rate by 25 bps to 3.75%-4.00%, marking its first rate hike since July 2023. The decision came amid persistent inflationary pressures, with the Fed stating that inflation remains elevated and that the latest rate increase would support a more timely return toward its 2% inflation target. The Fed’s updated projections indicate that 16 of 18 policymakers expect at least one more 25-bps rate hike by the end of 2026, taking the policy rate to 4.00%-4.25%. Policymakers also raised their 2026 inflation forecast, reflecting continued concerns over price pressures, particularly from higher energy costs. The Fed’s hawkish stance provides a positive backdrop for the USD and weigh on metal prices. This may keep the impact on INR relatively contained, with oil prices, capital flows and RBI intervention remaining key drivers.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 7.1% on a monthly basis due to raw material price surge.
Base metals:
- LME 3M copper are up 2% on a weekly basis supported by high China premium, and drawdown in SHFE inventory. However upside remains capped by rate hike pressures, tariff clarity, and geopolitical tensions.
- Aluminum prices are up 0.3% due to renewed tensions supporting energy prices and risk premium. However, gradual recovery from GCC and rate hike expectations will cap any significant upside.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For August 2026, Saudi Aramco Contract Prices (CPs) rebounded to USD 620/ton for propane and USD 640/ton for butane, compared with USD 580/ton and USD 600/ton, respectively, in July. This represents a 6.9% month-on-month increase in propane CPs and a 6.7% month-on-month increase in butane CPs.
- Sonatrach raised its August propane OSP by 4.2% m-o-m, from $518/ton to $540/ton, while the butane OSP was cut by 5.0%, from $600/ton to $570/ton.
- India’s commercial LPG prices eased further in August, with the 19 kg cylinder price in New Delhi declining by ₹192, from ₹2,930 in July to ₹2,738 as of 3 August 2026. Despite the recent correction, commercial LPG remains substantially above its pre-war level of ₹1,741/cylinder. In contrast, the 14.2 kg domestic LPG cylinder remained unchanged at ₹942, reflecting continued price stability for household consumers.
Impact Assessment of US/Israel-Iran Conflict
- Saudi Aramco loaded around 14 mln bbl of crude onto seven VLCCs at Gulf terminals on 20th Sep’26, signalling a partial recovery in exports after the East-West pipeline shutdown disrupted shipments through Yanbu.
- Saudi Gulf crude loadings have risen to around 3.7 MBpd since 12th Sep’26, from 2.9 MBpd earlier in Sep’26, while crude flows through the Strait of Hormuz averaged 2.9 MBpd over the past six days, contributing to easing supply concerns over supply disruptions.
- Russia’s ESPO Blend crude rose above 120 USD/bbl, supported by stronger Chinese demand amid Middle East supply disruptions, while record premiums to Brent and potential US tariffs on Russian oil further tightened the market and raised global oil prices.
- According to PPAC data, India’s crude oil imports fell 11% month-on-month to 19.01 mln tons in Aug’26 and declined 3% YoY from 19.60 mln tons a year earlier.
- India faces a policy trade-off as Russian crude accounts for more than 40% of its oil imports, with reducing purchases potentially raising domestic fuel costs, while continuing them could expose Indian exports to proposed US tariffs of up to 100%. With Indian refiners already securing Russian crude for Sep’26 and Oct’26, the issue could further complicate ongoing US–India trade negotiations.
- Russia’s Moscow refinery, operated by Gazprom Neft, has halted crude processing after a Ukrainian drone attack caused fires at both primary crude distillation units, with repairs potentially taking several weeks.
- The refinery processes around 0.23 MBpd of crude, comprising the 0.12 MBpd AVT-6 unit and 0.11 MBpd EURO+ unit, meaning the outage could temporarily remove its full 0.23 MBpd processing capacity.
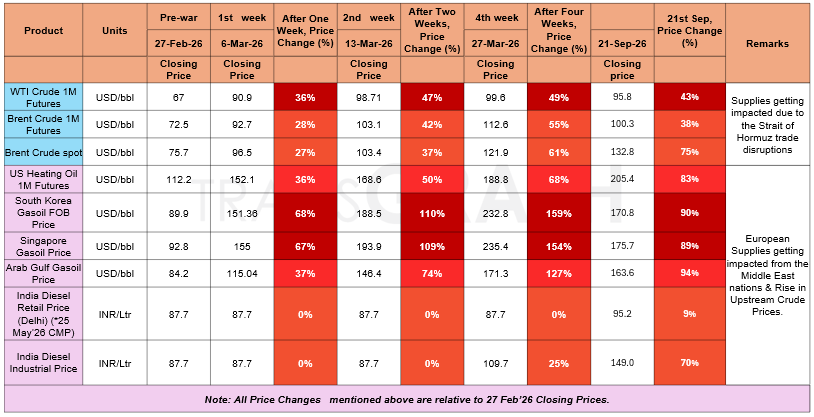
War Impact on Crude Oil & Gasoil/Diesel Prices
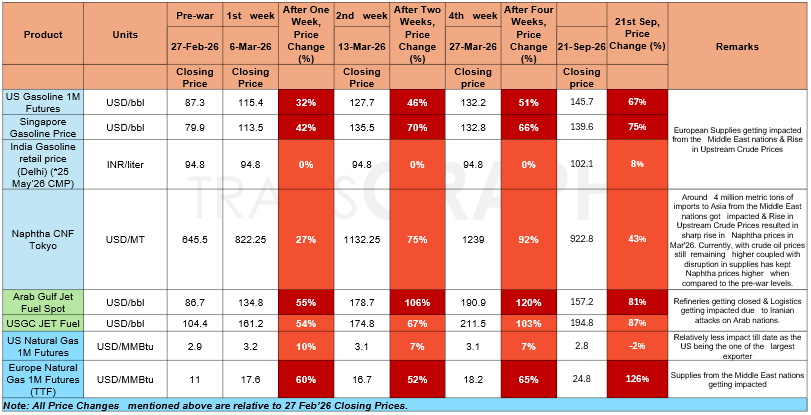
War Impact on Gasoline, ATF & Natural Gas Prices
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
War Front: Escalation Spreads to Saudi Arabia and Red Sea.
The war continued to widen as Houthi attacks on Saudi Arabia triggered further Saudi airstrikes in Yemen and expanded security alerts across the kingdom, including near Mecca, while shipping through the Strait of Hormuz fell to just four vessels on Tuesday. The disruption to Hormuz and Saudi oil infrastructure is keeping energy markets tight, with Brent above USD 107/bbl, increasing geopolitical risk premiums and raising energy and logistics risks for GCC aluminum smelters. although crude oil prices eased on Wednesday after a larger-than-expected build in U.S. crude inventories.
The U.S Federal Reserve raised its benchmark interest rate by 25 bps to 3.75%-4.00%, marking its first rate hike since July 2023. The decision came amid persistent inflationary pressures, with the Fed stating that inflation remains elevated and that the latest rate increase would support a more timely return toward its 2% inflation target. The Fed’s updated projections indicate that 16 of 18 policymakers expect at least one more 25-bps rate hike by the end of 2026, taking the policy rate to 4.00%-4.25%. Policymakers also raised their 2026 inflation forecast, reflecting continued concerns over price pressures, particularly from higher energy costs. The Fed’s hawkish stance provides a positive backdrop for the USD and weigh on metal prices. This may keep the impact on INR relatively contained, with oil prices, capital flows and RBI intervention remaining key drivers.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 7.1% on a monthly basis due to raw material price surge.
Base metals:
- LME 3M copper are up 2% on a weekly basis supported by high China premium, and drawdown in SHFE inventory. However upside remains capped by rate hike pressures, tariff clarity, and geopolitical tensions.
- Aluminum prices are up 0.3% due to renewed tensions supporting energy prices and risk premium. However, gradual recovery from GCC and rate hike expectations will cap any significant upside.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For August 2026, Saudi Aramco Contract Prices (CPs) rebounded to USD 620/ton for propane and USD 640/ton for butane, compared with USD 580/ton and USD 600/ton, respectively, in July. This represents a 6.9% month-on-month increase in propane CPs and a 6.7% month-on-month increase in butane CPs.
- Sonatrach raised its August propane OSP by 4.2% m-o-m, from $518/ton to $540/ton, while the butane OSP was cut by 5.0%, from $600/ton to $570/ton.
- India’s commercial LPG prices eased further in August, with the 19 kg cylinder price in New Delhi declining by ₹192, from ₹2,930 in July to ₹2,738 as of 3 August 2026. Despite the recent correction, commercial LPG remains substantially above its pre-war level of ₹1,741/cylinder. In contrast, the 14.2 kg domestic LPG cylinder remained unchanged at ₹942, reflecting continued price stability for household consumers.
Impact Assessment of US/Israel-Iran Conflict
- Traffic through the Strait of Hormuz has fallen sharply amid continued US-Iran tensions, with only 12 commodity vessels transiting over the weekend compared with 35 the previous weekend, although some Middle Eastern oil exports continue via tankers with transponders switched off.
- Saudi Arabia has increased crude exports through the Strait of Hormuz following disruptions to its East-West pipeline, with exports recovering to over 4 MBpd in Sep’26 till date and Saudi crude shipments through the strait averaging 2.9 MBpd in recent days.
- Russia’s ESPO Blend crude rose above 120 USD/bbl, supported by stronger Chinese demand amid Middle East supply disruptions, while record premiums to Brent and potential US tariffs on Russian oil further tightened the market and raised global oil prices.
- According to PPAC data, India’s crude oil imports fell 11% month-on-month to 19.01 mln tons in Aug’26 and declined 3% YoY from 19.60 mln tons a year earlier.
- India faces a policy trade-off as Russian crude accounts for more than 40% of its oil imports, with reducing purchases potentially raising domestic fuel costs, while continuing them could expose Indian exports to proposed US tariffs of up to 100%. With Indian refiners already securing Russian crude for Sep’26 and Oct’26, the issue could further complicate ongoing US–India trade negotiations.
- China’s refinery throughput increased by 11.2% MoM to 13.91MBpd in Aug’26, marking the second consecutive monthly rise, supported by stronger fuel exports after restrictions were eased in mid Jul’26.However, throughput remained 6.9% lower YoY, while domestic crude production rose by 0.8% YoY to 4.34 MBpd.
- China’s seaborne crude arrivals are expected to recover to around 8 MBpd in Sep’26–Oct’26, supported by ample onshore inventories, although an estimated 0.639 MBpd inventory draw in Aug’26 highlights tighter stock levels. Meanwhile, Jan’26–Aug’26 refinery throughput stood at 13.7 MBpd, down by 6.6% YoY, while crude production increased by 0.9% to 4.42 MBpd.
- Russia’s YANOS refinery, with a total crude-processing capacity of 300 kbpd, halted operations after a Ukrainian drone attack damaged its AVT-3 crude distillation unit (126 kbpd), while another AVT-4 unit (105 kbpd) remains under repair from a previous attack, potentially affecting a significant portion of the refinery’s throughput.
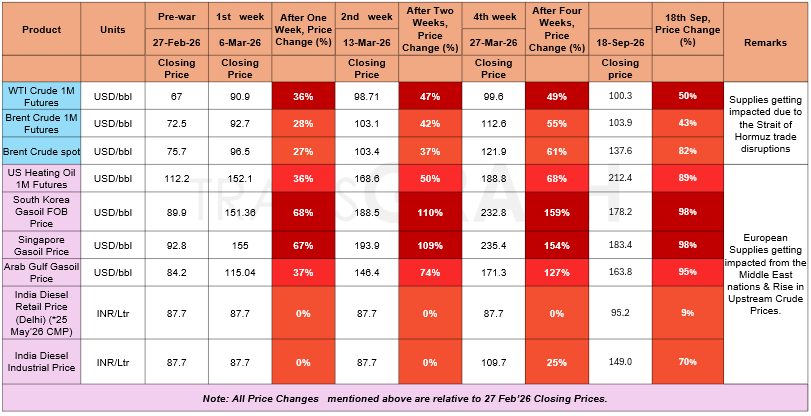
War Impact on Crude Oil & Gasoil/Diesel Prices
War Impact on Gasoline, ATF & Natural Gas Prices
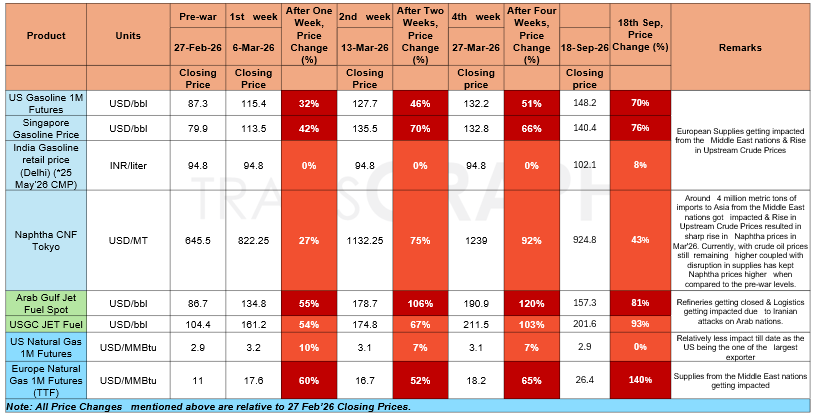
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
War Front: Escalation Spreads to Saudi Arabia and Red Sea.
The war continued to widen as Houthi attacks on Saudi Arabia triggered further Saudi airstrikes in Yemen and expanded security alerts across the kingdom, including near Mecca, while shipping through the Strait of Hormuz fell to just four vessels on Tuesday. The disruption to Hormuz and Saudi oil infrastructure is keeping energy markets tight, with Brent above USD 107/bbl, increasing geopolitical risk premiums and raising energy and logistics risks for GCC aluminum smelters. although crude oil prices eased on Wednesday after a larger-than-expected build in U.S. crude inventories.
The U.S Federal Reserve raised its benchmark interest rate by 25 bps to 3.75%-4.00%, marking its first rate hike since July 2023. The decision came amid persistent inflationary pressures, with the Fed stating that inflation remains elevated and that the latest rate increase would support a more timely return toward its 2% inflation target. The Fed’s updated projections indicate that 16 of 18 policymakers expect at least one more 25-bps rate hike by the end of 2026, taking the policy rate to 4.00%-4.25%. Policymakers also raised their 2026 inflation forecast, reflecting continued concerns over price pressures, particularly from higher energy costs. The Fed’s hawkish stance provides a positive backdrop for the USD and weigh on metal prices. This may keep the impact on INR relatively contained, with oil prices, capital flows and RBI intervention remaining key drivers.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 7.1% on a monthly basis due to raw material price surge.
Base metals:
- LME 3M copper are up 2% on a weekly basis supported by high China premium, and drawdown in SHFE inventory. However upside remains capped by rate hike pressures, tariff clarity, and geopolitical tensions.
- Aluminum prices are up 0.3% due to renewed tensions supporting energy prices and risk premium. However, gradual recovery from GCC and rate hike expectations will cap any significant upside.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For August 2026, Saudi Aramco Contract Prices (CPs) rebounded to USD 620/ton for propane and USD 640/ton for butane, compared with USD 580/ton and USD 600/ton, respectively, in July. This represents a 6.9% month-on-month increase in propane CPs and a 6.7% month-on-month increase in butane CPs.
- Sonatrach raised its August propane OSP by 4.2% m-o-m, from $518/ton to $540/ton, while the butane OSP was cut by 5.0%, from $600/ton to $570/ton.
- India’s commercial LPG prices eased further in August, with the 19 kg cylinder price in New Delhi declining by ₹192, from ₹2,930 in July to ₹2,738 as of 3 August 2026. Despite the recent correction, commercial LPG remains substantially above its pre-war level of ₹1,741/cylinder. In contrast, the 14.2 kg domestic LPG cylinder remained unchanged at ₹942, reflecting continued price stability for household consumers.
Impact Assessment of US/Israel-Iran Conflict
- Market grapevine indicates that Saudi Aramco is offering additional crude cargoes to Asian refiners via ship-to-ship transfers off Oman’s Sohar port to bypass Strait of Hormuz risks after drone attacks disrupted the East-West pipeline and suspended Yanbu loadings, while increased Gulf loadings and potential shipment delays or cancellations highlight ongoing regional supply constraints.
- Strait of Hormuz vessel traffic fell to 4 transits on Tuesday from 7 the previous day, far below the 10-day average of 18, with no VLCCs or LNG tankers recorded, while Bab el-Mandeb traffic remained relatively stable at 22 vessels versus 24 a day earlier.
- China’s refinery throughput increased by 11.2% MoM to 13.91MBpd in Aug’26, marking the second consecutive monthly rise, supported by stronger fuel exports after restrictions were eased in mid Jul’26.However, throughput remained 6.9% lower YoY, while domestic crude production rose by 0.8% YoY to 4.34 MBpd.
- China’s seaborne crude arrivals are expected to recover to around 8 MBpd in Sep’26–Oct’26, supported by ample onshore inventories, although an estimated 0.639 MBpd inventory draw in Aug’26 highlights tighter stock levels. Meanwhile, Jan’26–Aug’26 refinery throughput stood at 13.7 MBpd, down by 6.6% YoY, while crude production increased by 0.9% to 4.42 MBpd.
- China’s refinery throughput increased by 11.2% MoM to 13.91MBpd in Aug’26, marking the second consecutive monthly rise, supported by stronger fuel exports after restrictions were eased in mid Jul’26.However, throughput remained 6.9% lower YoY, while domestic crude production rose by 0.8% YoY to 4.34 MBpd.
- China’s seaborne crude arrivals are expected to recover to around 8 MBpd in Sep’26–Oct’26, supported by ample onshore inventories, although an estimated 0.639 MBpd inventory draw in Aug’26 highlights tighter stock levels. Meanwhile, Jan’26–Aug’26 refinery throughput stood at 13.7 MBpd, down by 6.6% YoY, while crude production increased by 0.9% to 4.42 MBpd.
- Ukrainian drone strikes are disrupting Russian refining operations and tightening regional fuel supplies with 3 of Russia’s 6 largest diesel producing refineries accounting for around 50% of the country’s diesel output either halting or sharply reducing production in Sep’26 with Kirishi refinery shutting completely, while NORSI and Volgograd are operating at only around 25% of capacity.
- The IEA expects global oil supply to decline by 5.7 MBpd (6.0%) in 2026, deeper than its earlier forecast of drop of around 4.0%, as Middle East conflict delays the recovery of Gulf flows into 2027. Global oil demand is also projected to fall by 2.5 MBpd, versus the previous estimate of a 1.6 MBpd decline, while inventories dropped by 3.1 MBpd in Aug’26 to their lowest level since 2023.
- Saudi Arabia’s crude supply fell by 2.30 MBpd MoM to 6.00 MBpd in Aug’26, the lowest in over 30 years, following attacks on key energy infrastructure and shipping routes. The IEA also cut its 2026 Saudi crude supply forecast by 0.88 MBpd to 7.60 MBpd, while crude loadings declined to 3.50 MBpd.
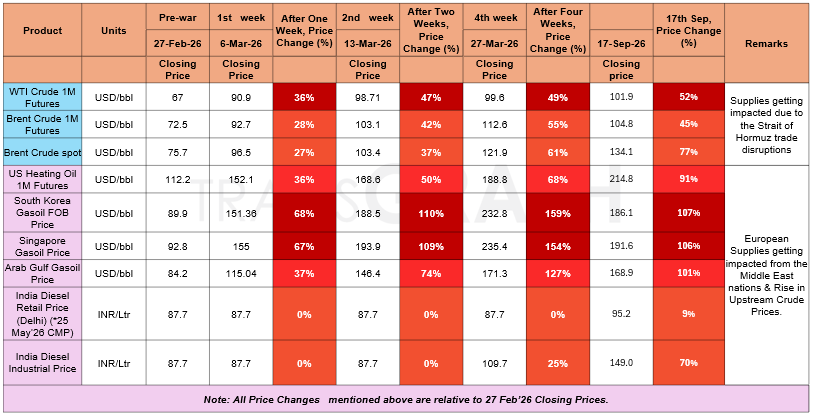
War Impact on Crude Oil & Gasoil/Diesel Prices
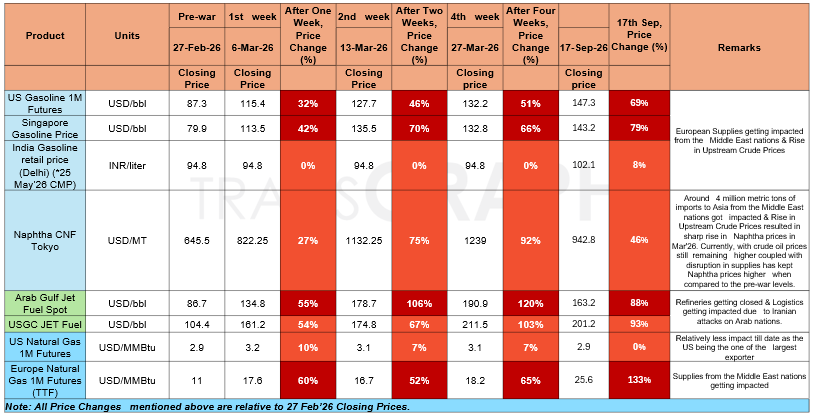
War Impact on Gasoline, ATF & Natural Gas Prices
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
War Front: Escalation Spreads to Saudi Arabia and Red Sea.
The war continued to widen as Houthi attacks on Saudi Arabia triggered further Saudi airstrikes in Yemen and expanded security alerts across the kingdom, including near Mecca, while shipping through the Strait of Hormuz fell to just four vessels on Tuesday. The disruption to Hormuz and Saudi oil infrastructure is keeping energy markets tight, with Brent above USD 107/bbl, increasing geopolitical risk premiums and raising energy and logistics risks for GCC aluminum smelters. although crude oil prices eased on Wednesday after a larger-than-expected build in U.S. crude inventories.
The U.S Federal Reserve raised its benchmark interest rate by 25 bps to 3.75%-4.00%, marking its first rate hike since July 2023. The decision came amid persistent inflationary pressures, with the Fed stating that inflation remains elevated and that the latest rate increase would support a more timely return toward its 2% inflation target. The Fed’s updated projections indicate that 16 of 18 policymakers expect at least one more 25-bps rate hike by the end of 2026, taking the policy rate to 4.00%-4.25%. Policymakers also raised their 2026 inflation forecast, reflecting continued concerns over price pressures, particularly from higher energy costs. The Fed’s hawkish stance provides a positive backdrop for the USD and weigh on metal prices. This may keep the impact on INR relatively contained, with oil prices, capital flows and RBI intervention remaining key drivers.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 7.1% on a monthly basis due to raw material price surge.
Base metals:
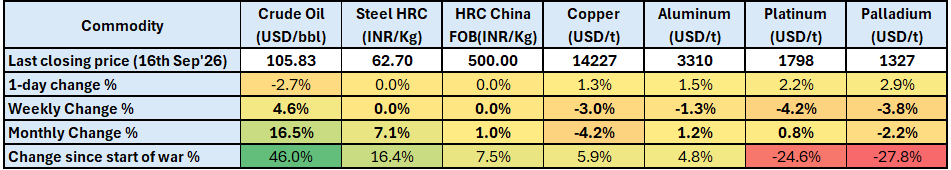
- LME 3M copper are down 3% on a weekly basis supported by stronger dollar, rate hike, and market moving back into contango structure. Copper prices fell sharply after the White House delayed decision on tariffs on refined copper.
- Aluminum prices are down 1.3% on a weekly basis due to pressure from rate hike, recovering GCC smelter production improving regional availability, and a strong US dollar offsetting support from renewed tensions in West Asia.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For August 2026, Saudi Aramco Contract Prices (CPs) rebounded to USD 620/ton for propane and USD 640/ton for butane, compared with USD 580/ton and USD 600/ton, respectively, in July. This represents a 6.9% month-on-month increase in propane CPs and a 6.7% month-on-month increase in butane CPs.
- Sonatrach raised its August propane OSP by 4.2% m-o-m, from $518/ton to $540/ton, while the butane OSP was cut by 5.0%, from $600/ton to $570/ton.
- India’s commercial LPG prices eased further in August, with the 19 kg cylinder price in New Delhi declining by ₹192, from ₹2,930 in July to ₹2,738 as of 3 August 2026. Despite the recent correction, commercial LPG remains substantially above its pre-war level of ₹1,741/cylinder. In contrast, the 14.2 kg domestic LPG cylinder remained unchanged at ₹942, reflecting continued price stability for household consumers.
Impact Assessment of US/Israel-Iran Conflict
- Market grapevine indicates that Saudi Aramco is offering additional crude cargoes to Asian refiners via ship-to-ship transfers off Oman’s Sohar port to bypass Strait of Hormuz risks after drone attacks disrupted the East-West pipeline and suspended Yanbu loadings, while increased Gulf loadings and potential shipment delays or cancellations highlight ongoing regional supply constraints.
- Strait of Hormuz vessel traffic fell to 4 transits on Tuesday from 7 the previous day, far below the 10-day average of 18, with no VLCCs or LNG tankers recorded, while Bab el-Mandeb traffic remained relatively stable at 22 vessels versus 24 a day earlier.
- China’s refinery throughput increased by 11.2% MoM to 13.91MBpd in Aug’26, marking the second consecutive monthly rise, supported by stronger fuel exports after restrictions were eased in mid Jul’26.However, throughput remained 6.9% lower YoY, while domestic crude production rose by 0.8% YoY to 4.34 MBpd.
- China’s seaborne crude arrivals are expected to recover to around 8 MBpd in Sep’26–Oct’26, supported by ample onshore inventories, although an estimated 0.639 MBpd inventory draw in Aug’26 highlights tighter stock levels. Meanwhile, Jan’26–Aug’26 refinery throughput stood at 13.7 MBpd, down by 6.6% YoY, while crude production increased by 0.9% to 4.42 MBpd.
- China’s refinery throughput increased by 11.2% MoM to 13.91MBpd in Aug’26, marking the second consecutive monthly rise, supported by stronger fuel exports after restrictions were eased in mid Jul’26.However, throughput remained 6.9% lower YoY, while domestic crude production rose by 0.8% YoY to 4.34 MBpd.
- China’s seaborne crude arrivals are expected to recover to around 8 MBpd in Sep’26–Oct’26, supported by ample onshore inventories, although an estimated 0.639 MBpd inventory draw in Aug’26 highlights tighter stock levels. Meanwhile, Jan’26–Aug’26 refinery throughput stood at 13.7 MBpd, down by 6.6% YoY, while crude production increased by 0.9% to 4.42 MBpd.
- Ukrainian drone strikes are disrupting Russian refining operations and tightening regional fuel supplies with 3 of Russia’s 6 largest diesel producing refineries accounting for around 50% of the country’s diesel output either halting or sharply reducing production in Sep’26 with Kirishi refinery shutting completely, while NORSI and Volgograd are operating at only around 25% of capacity.
- The IEA expects global oil supply to decline by 5.7 MBpd (6.0%) in 2026, deeper than its earlier forecast of drop of around 4.0%, as Middle East conflict delays the recovery of Gulf flows into 2027. Global oil demand is also projected to fall by 2.5 MBpd, versus the previous estimate of a 1.6 MBpd decline, while inventories dropped by 3.1 MBpd in Aug’26 to their lowest level since 2023.
- Saudi Arabia’s crude supply fell by 2.30 MBpd MoM to 6.00 MBpd in Aug’26, the lowest in over 30 years, following attacks on key energy infrastructure and shipping routes. The IEA also cut its 2026 Saudi crude supply forecast by 0.88 MBpd to 7.60 MBpd, while crude loadings declined to 3.50 MBpd.
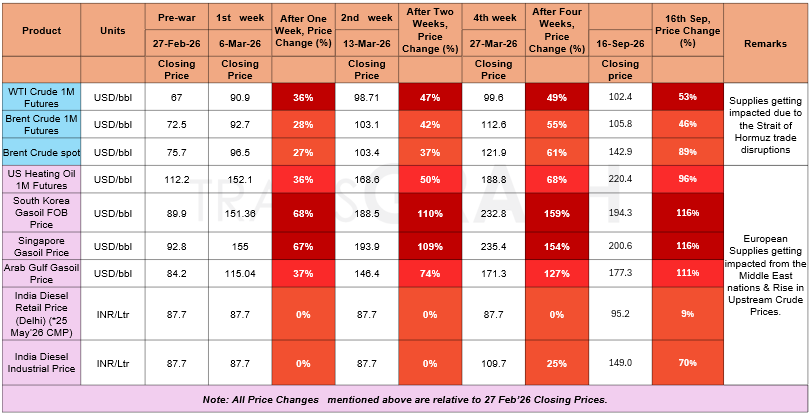
War Impact on Crude Oil & Gasoil/Diesel Prices
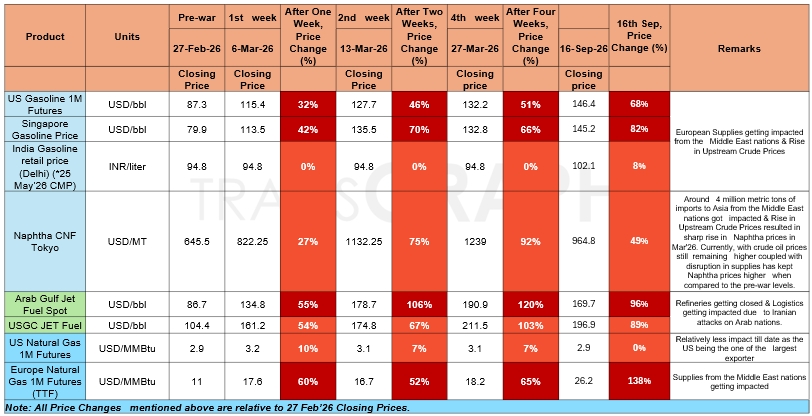
War Impact on Gasoline, ATF & Natural Gas Prices
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
War Front: Escalation Spreads to Saudi Arabia and Red Sea.
The war continued to widen as Houthi attacks on Saudi Arabia triggered further Saudi airstrikes in Yemen and expanded security alerts across the kingdom, including near Mecca, while shipping through the Strait of Hormuz fell to just four vessels on Tuesday. The disruption to Hormuz and Saudi oil infrastructure is keeping energy markets tight, with Brent above USD 107/bbl, increasing geopolitical risk premiums and raising energy and logistics risks for GCC aluminum smelters. although crude oil prices eased on Wednesday after a larger-than-expected build in U.S. crude inventories.
The U.S Federal Reserve raised its benchmark interest rate by 25 bps to 3.75%-4.00%, marking its first rate hike since July 2023. The decision came amid persistent inflationary pressures, with the Fed stating that inflation remains elevated and that the latest rate increase would support a more timely return toward its 2% inflation target. The Fed’s updated projections indicate that 16 of 18 policymakers expect at least one more 25-bps rate hike by the end of 2026, taking the policy rate to 4.00%-4.25%. Policymakers also raised their 2026 inflation forecast, reflecting continued concerns over price pressures, particularly from higher energy costs. The Fed’s hawkish stance provides a positive backdrop for the USD and weigh on metal prices. This may keep the impact on INR relatively contained, with oil prices, capital flows and RBI intervention remaining key drivers.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 7.1% on a monthly basis due to raw material price surge.
Base metals:
- LME 3M copper are down 3% on a weekly basis supported by stronger dollar, rate hike, and market moving back into contango structure. Copper prices fell sharply after the White House delayed decision on tariffs on refined copper.
- Aluminum prices are down 1.3% on a weekly basis due to pressure from rate hike, recovering GCC smelter production improving regional availability, and a strong US dollar offsetting support from renewed tensions in West Asia.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For August 2026, Saudi Aramco Contract Prices (CPs) rebounded to USD 620/ton for propane and USD 640/ton for butane, compared with USD 580/ton and USD 600/ton, respectively, in July. This represents a 6.9% month-on-month increase in propane CPs and a 6.7% month-on-month increase in butane CPs.
- Sonatrach raised its August propane OSP by 4.2% m-o-m, from $518/ton to $540/ton, while the butane OSP was cut by 5.0%, from $600/ton to $570/ton.
- India’s commercial LPG prices eased further in August, with the 19 kg cylinder price in New Delhi declining by ₹192, from ₹2,930 in July to ₹2,738 as of 3 August 2026. Despite the recent correction, commercial LPG remains substantially above its pre-war level of ₹1,741/cylinder. In contrast, the 14.2 kg domestic LPG cylinder remained unchanged at ₹942, reflecting continued price stability for household consumers.