- Iranian Foreign Minister Abbas Araqchi reiterated Tehran’s offer to reopen the Strait of Hormuz within seven days, subject to the lifting of the US blockade on Iranian ports, the removal of sanctions on Iranian oil exports and an end to hostilities across the region. However, Washington and Tehran remained divided over the terms and sequencing of negotiations, particularly regarding Iran’s nuclear programme, leaving uncertainty over the reopening of the strategic waterway.
- Egypt signalled its readiness to provide support to Saudi Arabia amid escalating attacks by Iran backed Houthi forces in Yemen, following reported strikes targeting Saudi infrastructure. The developments heightened concerns over regional security and the potential for further disruptions to Middle Eastern energy facilities and shipping routes.
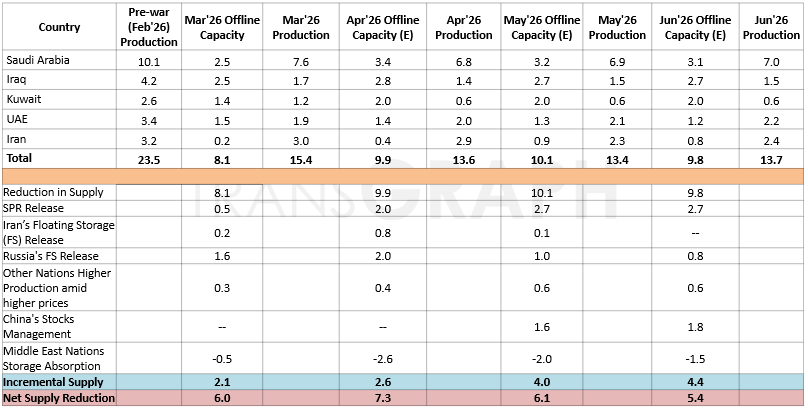
- Crude oil flows from the Gulf declined sharply to around 8.5 MBpd, compared with more than 20 MBpd in the previous week, amid escalating maritime security risks, with at least 10 confirmed incidents involving commercial vessels reported during the period.
- Vessel traffic through the Strait of Hormuz fell to 5 crossings on 17th Oct’26, comprising one inbound and four outbound vessels, compared with 11 on 16th Oct and 14 on 15th Oct’26. Separately, on 16th Oct’26, a Liberia flagged Suezmax tanker was damaged in a reported small boat attack near Al Jubail, Saudi Arabia, raising concerns over crude oil shipment delays and potential supply disruptions.
- US decision to waive certain sanctions and tariff restrictions on Russian fuel supplies raised expectations of increased diesel availability, with supplies reportedly projected at 2.3 mln bbl in Oct’26, potentially rising to 7.6 mln bbl in subsequent months.
- The Trump administration is considering easing sanctions on shadow fleet vessels to increase the flow of crude oil and petroleum products from the Gulf and help reduce record-high global tanker freight rates, which have made US crude less competitive for Asian refiners.
- On 15th Oct’26, Ukraine launched a drone attack on Rosneft’s Ryazan refinery in Russia, triggering a fire at the facility, which accounts for nearly 5% of Russia’s refining capacity and supplies fuel to Moscow, raising concerns over potential disruptions to Russian fuel production and domestic supplies.
- Ukraine launched a large-scale drone attack on St Petersburg on 18th Oct’26, targeting energy infrastructure, including an oil terminal and an oil depot, triggering fires and causing casualties, according to local reports. The incident marked a further escalation in Ukraine’s campaign against Russian energy assets.
- US President Donald Trump stated that Washington would not launch an attack on Iran before the 3rd Nov’26 midterm elections, citing ongoing productive discussions with Tehran aimed at resolving the conflict.
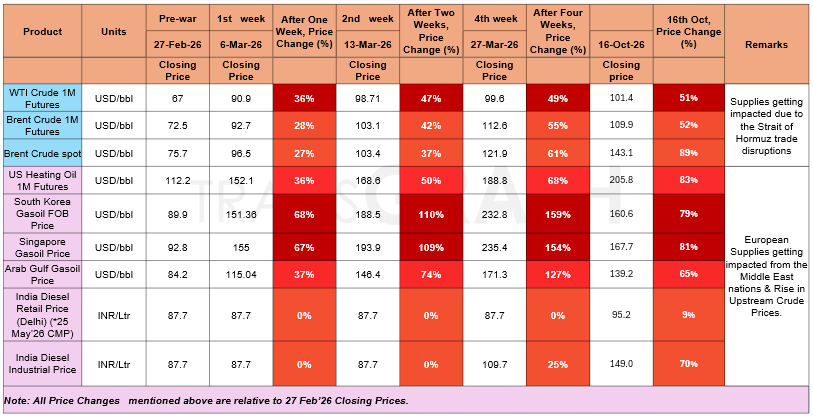
War Impact on Crude Oil & Gasoil/Diesel Prices
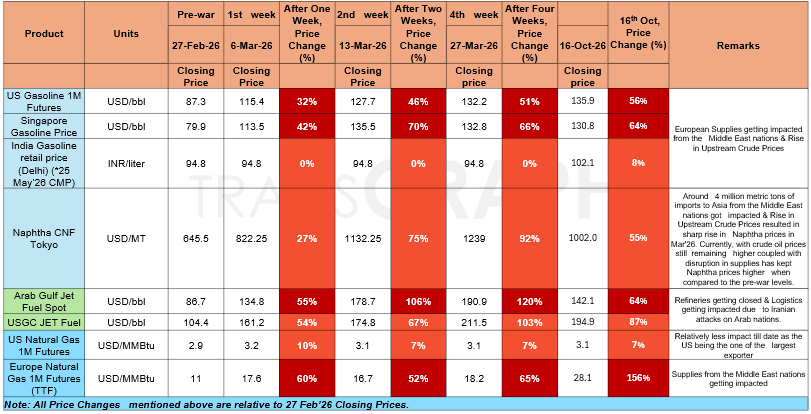
War Impact on Gasoline, ATF & Natural Gas Prices
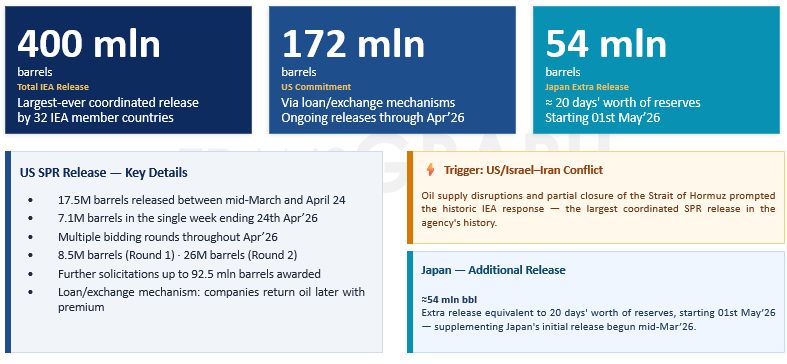
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
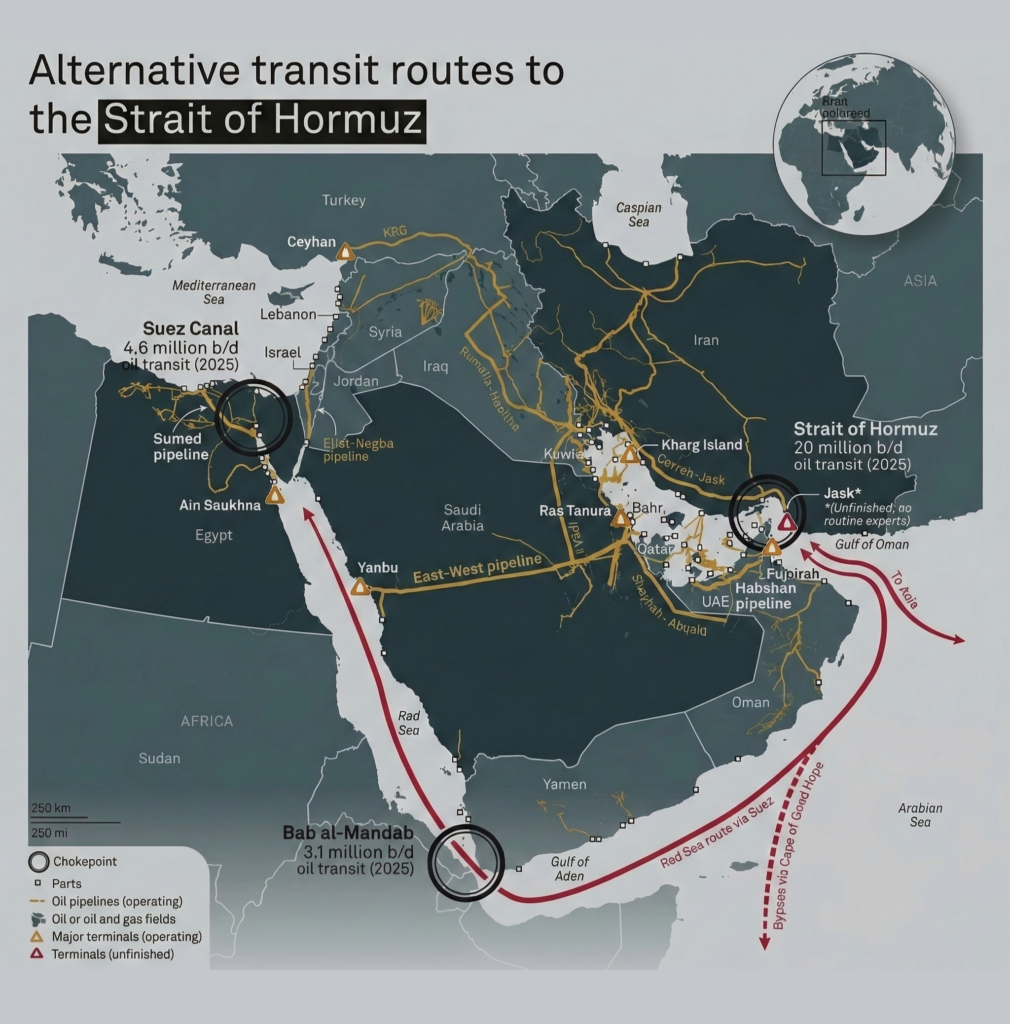
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
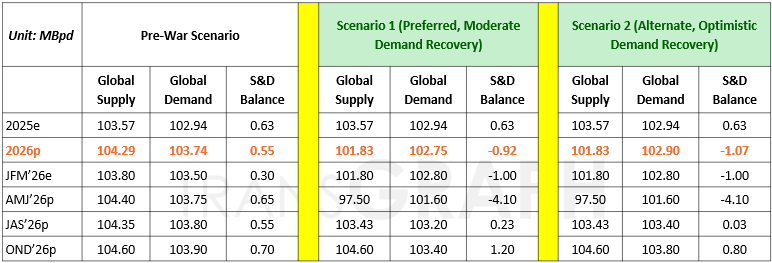
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
War Front: U.S.–Iran tensions remained high over the weekend, with fresh threats to commercial shipping and no significant progress in diplomatic negotiations. Iran claimed that two supertankers struck naval mines on Saturday. Washington and Tehran remain at odds over the terms and sequencing of negotiations, particularly Iran’s nuclear programme. Meanwhile, Egypt expressed support for Saudi Arabia amid intensified Houthi attacks on Saudi infrastructure, raising concerns about a wider regional escalation.
Steel:
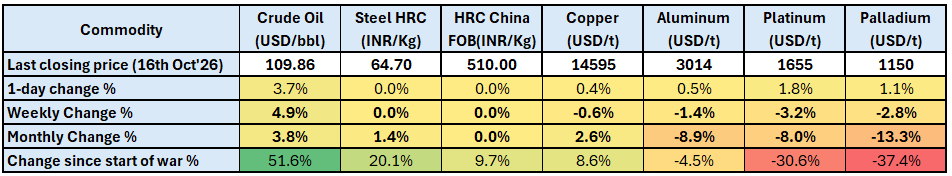
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 1.4% on a monthly basis due to raw material price surge and stronger demand from auto sector.
Base metals:
- LME 3M copper are up by 2.6% on a monthly basis as support from weaker job data, reduced rate hike expectations, several supply disruptions in Chile, backwardation structure was capped by progress in restart of Key Chile mines and geopolitical tensions.
- Aluminum prices are down 1.4% on a weekly basis due to gradual recovery from GCC and stronger dollar despite tensions in the middle east.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For October, Saudi Aramco CP was set at USD 680/ton for propane and USD 730/ton for butane, representing increases of USD 55/ton and USD 70/ton, respectively, from September levels. The propane-butane spread widened further to USD 50/ton, compared with USD 35/ton in September and USD 20/ton in August, indicating continued relative strength in butane pricing and tighter butane availability compared with propane. The larger month-on-month increase in butane also points to a stronger rise in butane market tightness entering October.
- Sonatrach increased its October propane OSP by USD 110/ton, from USD 560/ton in September to USD 670/ton. Meanwhile, the butane OSP increased by USD 140/ton, from USD 610/ton to USD 750/ton.
- US LPG prices strengthened across the board between 1 October and 8 October 2026, with propane rising by 8.6% to USD 466/ton from USD 429/ton. Butane increased by 7.6% to USD 738/ton from USD 686/ton, while the 50:50 LPG blend climbed by 8.0% to USD 601.77/ton from USD 557.28/ton. Notably, the Mont Belvieu 50:50 LPG blend crossed the USD 600/ton threshold for the first time since 2022, underscoring the strength of the current price rally. The simultaneous increase in propane and butane indicates broad-based upward pressure across the US LPG market rather than a rally driven by a single component.