- US President Donald Trump stated that Washington was engaged in productive discussions with Tehran and would not launch an attack on Iran before the 3rd Nov’26 midterm elections, easing immediate concerns over further military escalation.
- Oil movements through the Strait of Hormuz declined by approximately 27% from their wartime weekly peak to 10.1 MBpd, equivalent to around 74% of pre-war levels, with only seven commodity vessels crossing on 06th Oct’26 , the lowest number since 23rd Jul’26. Meanwhile, exports through alternative routes via the Gulf of Oman and the Red Sea increased to approximately 6.7 MBpd, partially offsetting the decline in Hormuz shipments.
- On 8th Oct’26, the chemical tanker Acers was struck by multiple projectiles approximately 51 nautical miles north of Madinat ash Shamal, Qatar, injuring crew members and raising concerns over maritime security and the safety of oil and energy shipments across the Persian Gulf.
- Iran threatened to block unauthorised oil shipping routes through the Strait of Hormuz amid intensifying tanker attacks, with vessel traffic falling to its lowest level in more than two months. The escalating maritime security risks are disrupting crude transportation and increasing uncertainty over the reliability of Middle Eastern oil exports.
- The US imposed new sanctions targeting 17 vessels, along with individuals and networks involved in transporting Iranian crude oil, petroleum products and petrochemicals, aiming to restrict Iran’s oil revenues and further constrain its crude-export channels.
- US President Donald Trump stated that Washington was engaged in productive discussions with Tehran and would not launch an attack on Iran before the 3rd Nov’26 midterm elections, easing immediate concerns over further military escalation.
- Hurricane related disruptions forced the shutdown of approximately 1.3 MBpd of US Gulf of Mexico crude production, equivalent to 62.9% of regional output, as Shell, Chevron and BP suspended operations at offshore facilities. The production losses could persist until weather conditions improve and safety inspections are completed, potentially tightening US crude supply in the near term.
- Chinese refiners are set to resume gasoline, diesel and jet fuel exports following a temporary suspension during the Golden Week holiday, with authorities approving approximately 3.7 mln tons of combined exports for Oct’26. The resumption is expected to improve regional fuel availability and ease supply tightness across Asian markets.
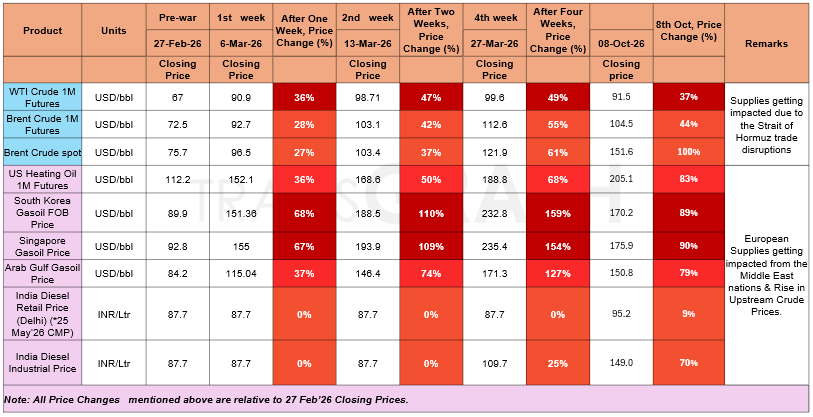
War Impact on Crude Oil & Gasoil/Diesel Prices
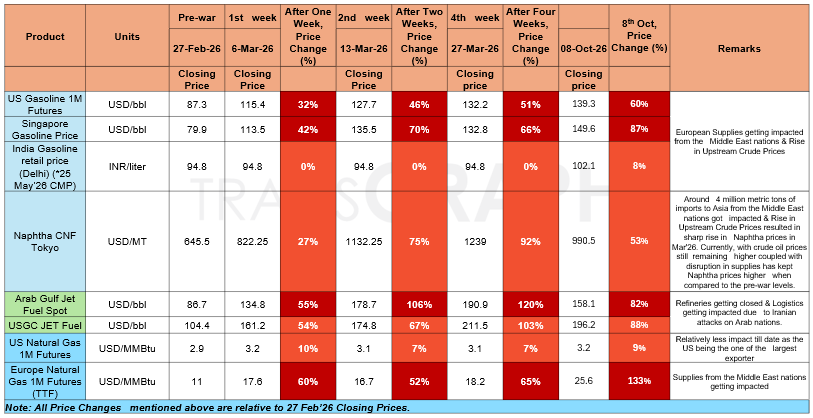
War Impact on Gasoline, ATF & Natural Gas Prices
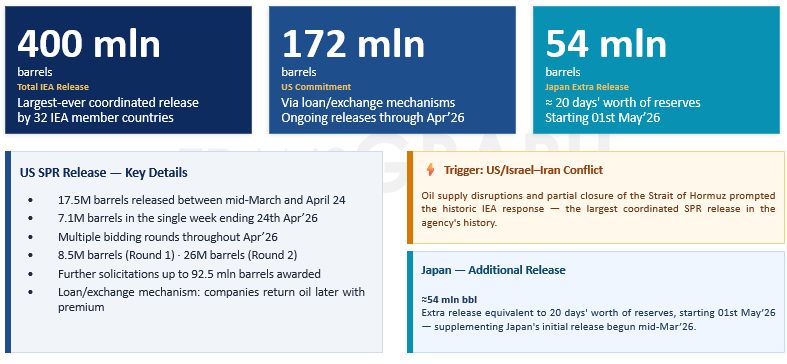
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
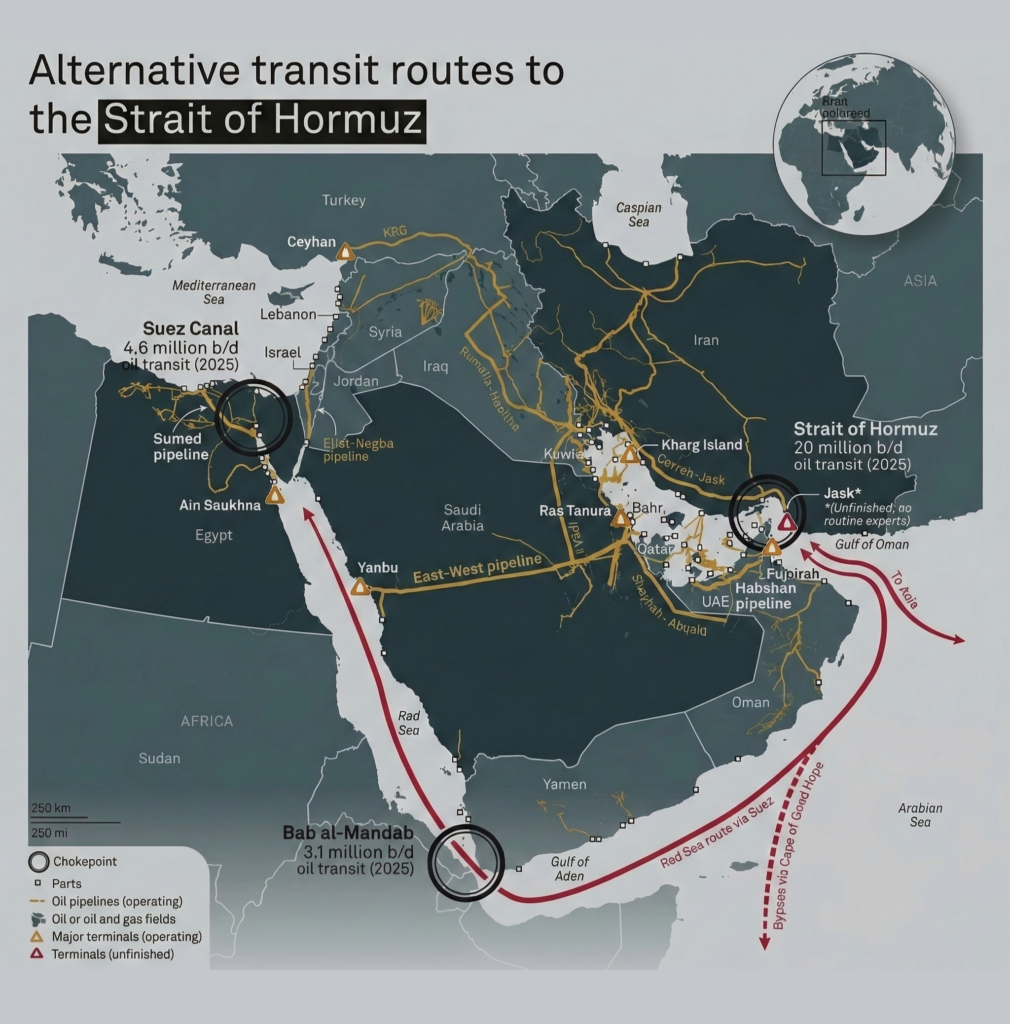
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
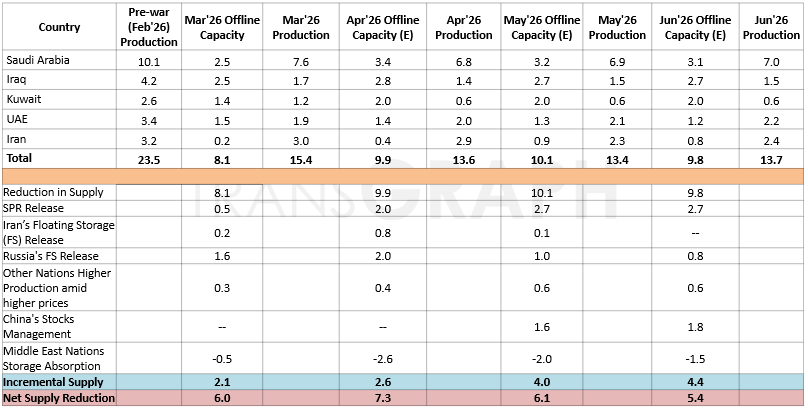
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
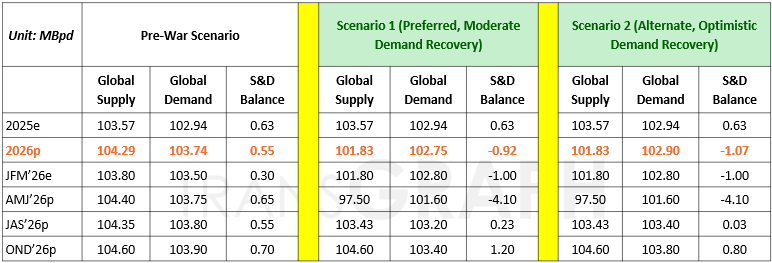
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
War Front: Yemen Escalation Raises Red Sea and Gulf Shipping Risks - Yemen fighting has intensified as Saudi-backed forces advance near the Bab el-Mandeb Strait, while Houthi attacks on Saudi infrastructure and continued tanker incidents around the Strait of Hormuz keep Gulf shipping risks elevated. At the same time, the U.S. is expanding its military presence in the Gulf, including an additional carrier and around 10,000 sailors and Marines, while diplomacy with Iran remains stalled.
US central bank viewed inflation as the biggest risk to their outlook, with most participants assessed that another increase in the fed funds target range would likely be appropriate by year end. This led to a higher Treasury yields ,strengthening the dollar’s interest rate differentials. However, September nonfarm payrolls increased by only 29K, well below expectations, adding to expectations that the Fed may have less scope for October Fed rate hike, along with dovish comments from New York Fed President John Williams, further limited the dollar’s upside.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
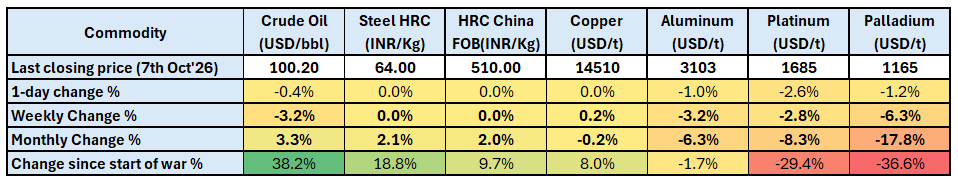
- Moreover, HRC prices are up by 2.1% on a monthly basis due to raw material price surge and stronger demand from auto sector.
Base metals:
- LME 3M copper are up by just 0.2% on a weekly basis as support from weaker job data, reduced rate hike expectations, several supply disruptions in Chile (Escondida, Radomiro Tomic, and Centinela), backwardation structure, and drawdown in SHFE inventory was capped by progress in Grasberg repairs and geopolitical tensions.
- Aluminum prices are down 3.2% due to gradual recovery from GCC and stronger dollar despite tensions in the middle east.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For October, Saudi Aramco CP was set at USD 680/ton for propane and USD 730/ton for butane, representing increases of USD 55/ton and USD 70/ton, respectively, from September levels. The propane-butane spread widened further to USD 50/ton, compared with USD 35/ton in September and USD 20/ton in August, indicating continued relative strength in butane pricing and tighter butane availability compared with propane. The larger month-on-month increase in butane also points to a stronger rise in butane market tightness entering October.
- Sonatrach increased its October propane OSP by USD 110/ton, from USD 560/ton in September to USD 670/ton. Meanwhile, the butane OSP increased by USD 140/ton, from USD 610/ton to USD 750/ton.
- US LPG prices strengthened across the board between 1 October and 8 October 2026, with propane rising by 8.6% to USD 466/ton from USD 429/ton. Butane increased by 7.6% to USD 738/ton from USD 686/ton, while the 50:50 LPG blend climbed by 8.0% to USD 601.77/ton from USD 557.28/ton. Notably, the Mont Belvieu 50:50 LPG blend crossed the USD 600/ton threshold for the first time since 2022, underscoring the strength of the current price rally. The simultaneous increase in propane and butane indicates broad-based upward pressure across the US LPG market rather than a rally driven by a single component.