- Saudi Arabia’s East-West Pipeline continued to restore crude export capacity, with the Energy Minister stating on 6th Oct’26 that cumulative crude volumes pumped through the pipeline to Yanbu had reached 5.8 mln bbl. The pipeline, which can transport around 4 MBpd, is being used as an alternative export route to the Strait of Hormuz amid ongoing regional disruptions.
- Saudi crude exports drove the recovery in Gulf flows in Sep’26, with Saudi shipments rising by 4.2 MBpd MoM to 6.6 MBpd, while overall Gulf flows excluding Iran recovered to more than 81% of pre-war levels.
- Iranian crude exports fell to zero in Sep’26 as the US blockade severely restricted outbound shipments, while floating Iranian crude inventories outside the blockade zone declined to around 45 mln bbl from approximately 100 mln bbl in late Jul’26, further tightening Iran’s export availability.
- Iraq’s 2027 draft budget assumes crude exports of around 4 MBpd, including Kurdistan volumes, while Baghdad is exploring alternative transportation routes because of disruption to Gulf shipments.
- According to the market grapevine ,US crude production is expected to reach a record high of 14.3 MBpd in 2027 amid rapidly declining global inventories and tight diesel markets linked to the Iran conflict.
- A developing storm was forecasted to become the first Atlantic hurricane of 2026, with offshore areas in its projected path accounting for around 15% of US crude production. The storm could also disrupt Gulf Coast refineries, which represent roughly 50% of US refining capacity, posing risks to both crude production and refining operations.
- Chinese independent refiners increased purchases of Iraqi Basrah Medium/Heavy crude and Qatar Al-Shaheen crude, securing at least 12 mln bbl for Oct’26–Nov’26 delivery, with total purchases estimated at 15–20 mln bbl, as Iranian crude imports fell to 0.59 MBpd in Sep’26, the lowest level since January 2023 which is prompting refiners to seek alternative supplies.
- Petrobras announced a new oil discovery off Brazil’s Amapá state on 2nd Oct’26 in ultra deep waters in the Equatorial Margin, an area considered one of the country’s most promising new oil frontiers.
- Venezuela’s 0.31 MBpd Cardón refinery was shut after a fire, highlighting the country’s paradox of rising crude exports but severely constrained domestic refining capacity and increasing reliance on imported fuel.
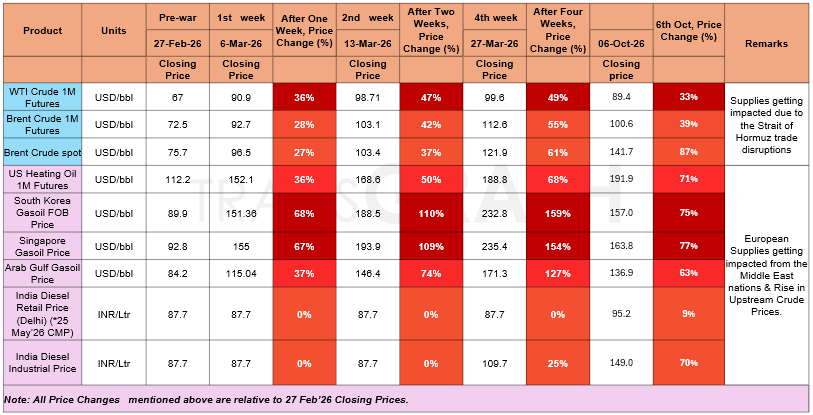
War Impact on Crude Oil & Gasoil/Diesel Prices
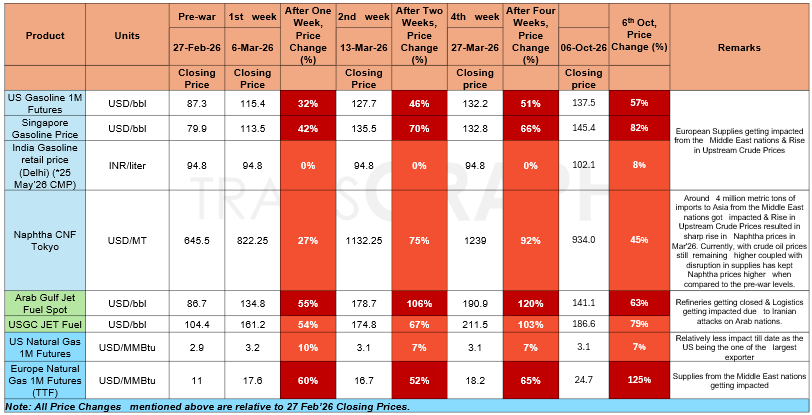
War Impact on Gasoline, ATF & Natural Gas Prices
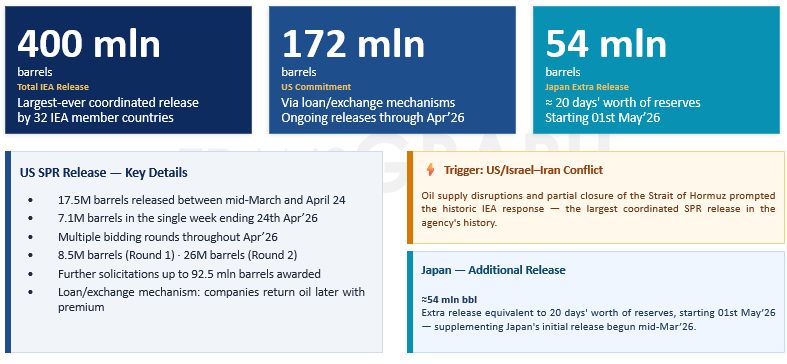
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
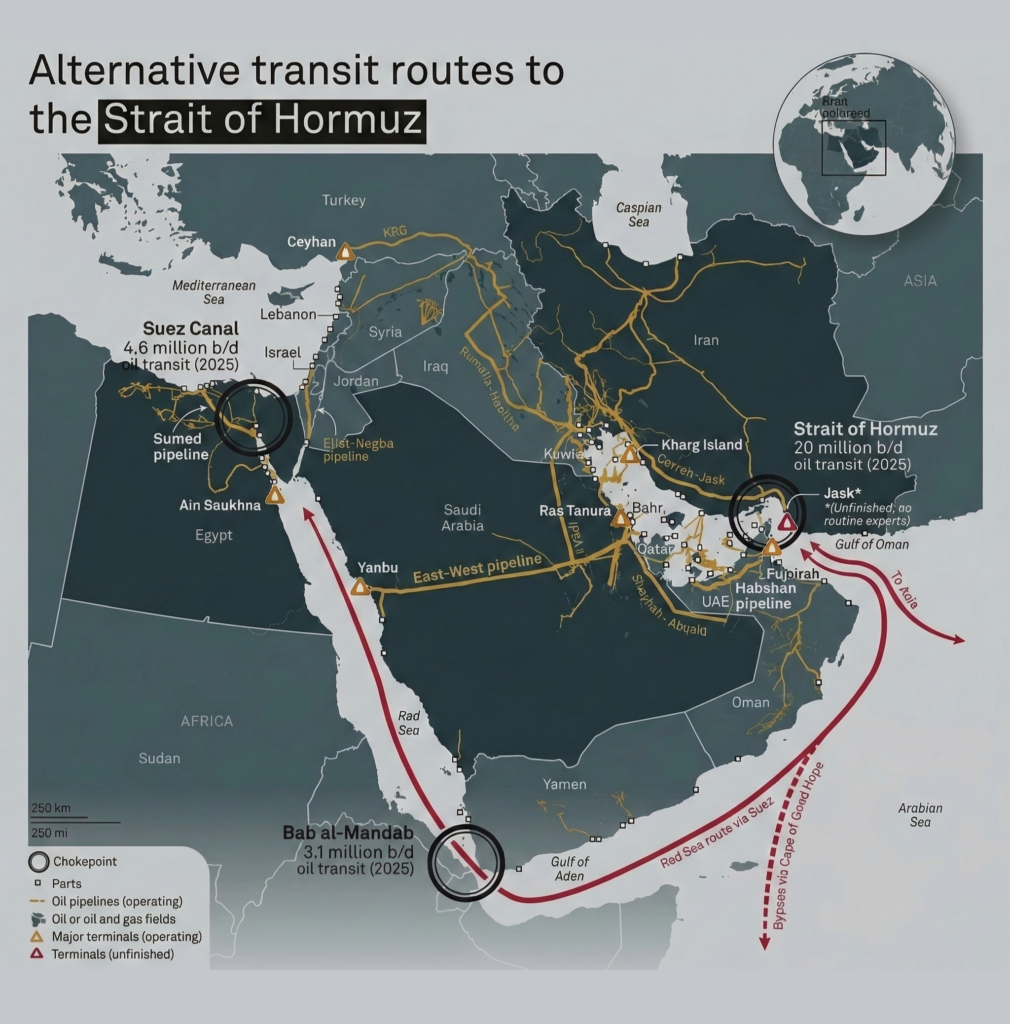
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
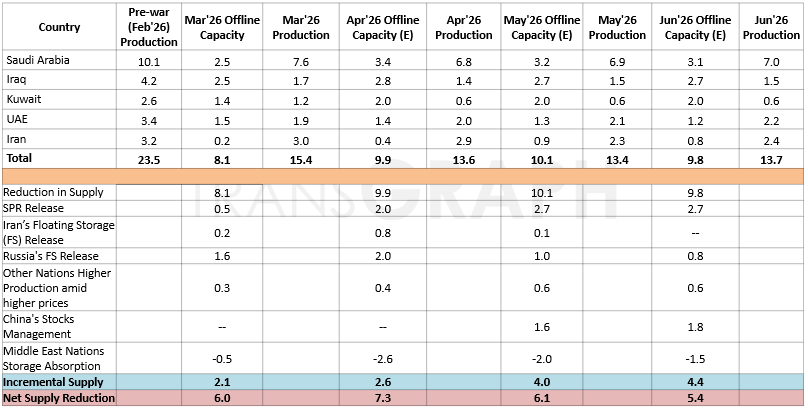
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
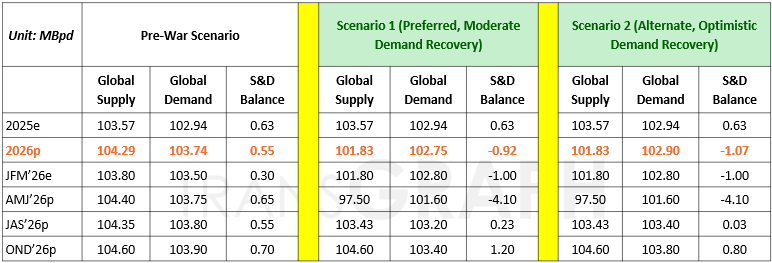
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
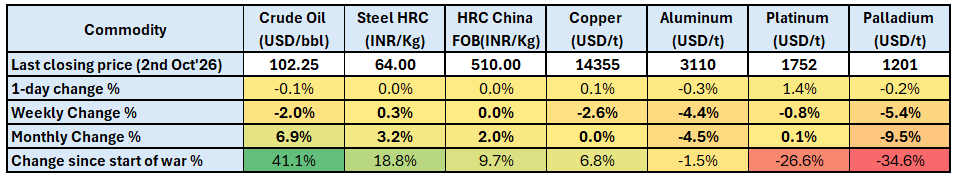
War Front: President Trump has indicated that US has rejected the latest peace deal. Fears of fresh attacks have risen amid breakdown in negotiations weighing on base metals. US President Donald Trump has rejected a news report claiming his administration offered Iran sanctions relief and access to frozen funds, calling the story a hoax on social media. Iranian Foreign Minister Abbas Araghchi says Tehran has held further indirect talks with the United States through Qatari mediators in New York, with Washington’s formal response expected by Tuesday.
The United States and China have agreed to reduce tariffs on $30 billion of goods and launch a dialogue on AI, both countries said following President Xi Jinping's visit to Washington. The tariff reductions would apply to US exports such as agricultural goods, wood and cosmetics, as well as US imports including small appliances, toys, decorations, a White House statement said on Friday.
Recently New York Fed President John Williams said there was “no urgency” to raise rates again. This reduced expectations of an immediate/October Fed hike: Saudi Arabia restarted flows through its East-West pipeline after repairs following drone attacks. September crude exports from Middle Eastern producers reached about 16.3 million barrels/day. The US offered to loan up to 40 million barrels from its Strategic Petroleum Reserve. This adds another potential source of crude supply and therefore put downward pressure on prices. These factors eased near-term supply concerns, reducing inflation pressure.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 3.2% on a monthly basis due to raw material price surge and stronger demand from auto sector.
Base metals:
- LME 3M copper are down 2.6% on a weekly basis as mid autumn festival slowed China consumption. Further, rejection of peace deal by US and stronger dollar is weighing on metals. However, backwardation structure, reduced rate hike expectations, and supply disruptions will provide some support.
- Aluminum prices are down 4.4% due to gradual recovery from GCC and stronger dollar despite tensions in the middle east.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For August 2026, Saudi Aramco Contract Prices (CPs) rebounded to USD 620/ton for propane and USD 640/ton for butane, compared with USD 580/ton and USD 600/ton, respectively, in July. This represents a 6.9% month-on-month increase in propane CPs and a 6.7% month-on-month increase in butane CPs.
- Sonatrach raised its August propane OSP by 4.2% m-o-m, from $518/ton to $540/ton, while the butane OSP was cut by 5.0%, from $600/ton to $570/ton.
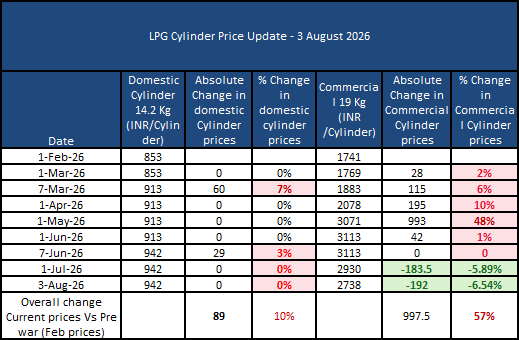
- India’s commercial LPG prices eased further in August, with the 19 kg cylinder price in New Delhi declining by ₹192, from ₹2,930 in July to ₹2,738 as of 3 August 2026. Despite the recent correction, commercial LPG remains substantially above its pre-war level of ₹1,741/cylinder. In contrast, the 14.2 kg domestic LPG cylinder remained unchanged at ₹942, reflecting continued price stability for household consumers.