- Saudi Aramco loaded around 14 mln bbl of crude onto seven VLCCs at Gulf terminals on 20th Sep’26, signalling a partial recovery in exports after the East-West pipeline shutdown disrupted shipments through Yanbu.
- Saudi Gulf crude loadings have risen to around 3.7 MBpd since 12th Sep’26, from 2.9 MBpd earlier in Sep’26, while crude flows through the Strait of Hormuz averaged 2.9 MBpd over the past six days, contributing to easing supply concerns over supply disruptions.
- Russia’s ESPO Blend crude rose above 120 USD/bbl, supported by stronger Chinese demand amid Middle East supply disruptions, while record premiums to Brent and potential US tariffs on Russian oil further tightened the market and raised global oil prices.
- According to PPAC data, India’s crude oil imports fell 11% month-on-month to 19.01 mln tons in Aug’26 and declined 3% YoY from 19.60 mln tons a year earlier.
- India faces a policy trade-off as Russian crude accounts for more than 40% of its oil imports, with reducing purchases potentially raising domestic fuel costs, while continuing them could expose Indian exports to proposed US tariffs of up to 100%. With Indian refiners already securing Russian crude for Sep’26 and Oct’26, the issue could further complicate ongoing US–India trade negotiations.
- Russia’s Moscow refinery, operated by Gazprom Neft, has halted crude processing after a Ukrainian drone attack caused fires at both primary crude distillation units, with repairs potentially taking several weeks.
- The refinery processes around 0.23 MBpd of crude, comprising the 0.12 MBpd AVT-6 unit and 0.11 MBpd EURO+ unit, meaning the outage could temporarily remove its full 0.23 MBpd processing capacity.
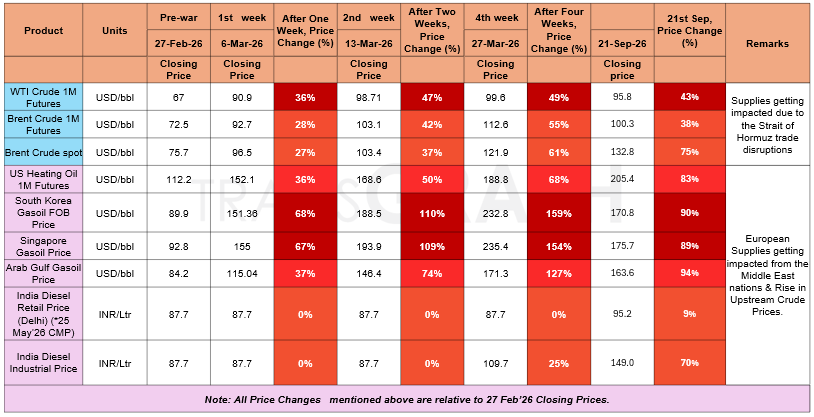
War Impact on Crude Oil & Gasoil/Diesel Prices
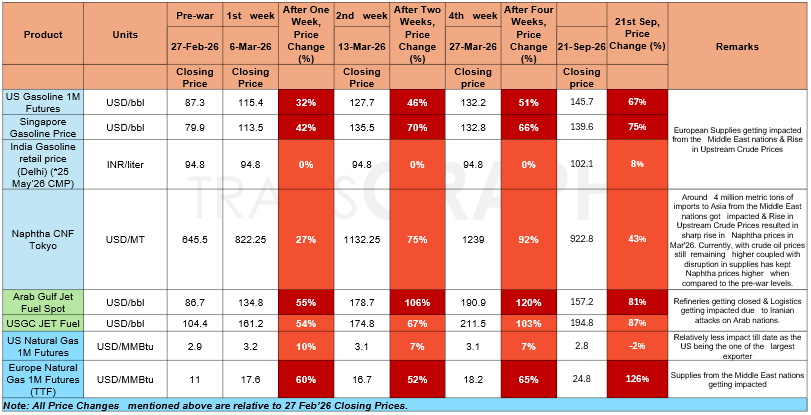
War Impact on Gasoline, ATF & Natural Gas Prices
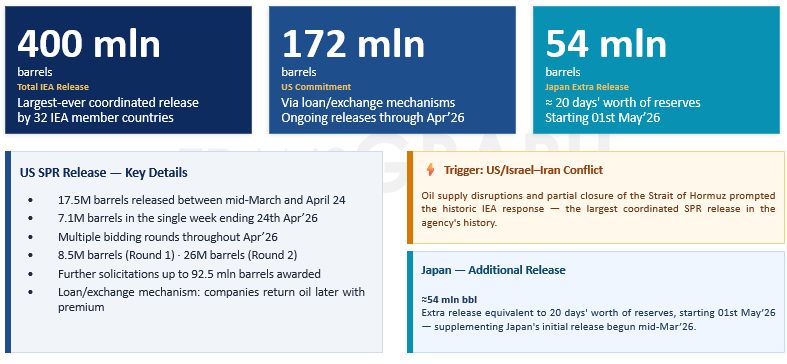
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
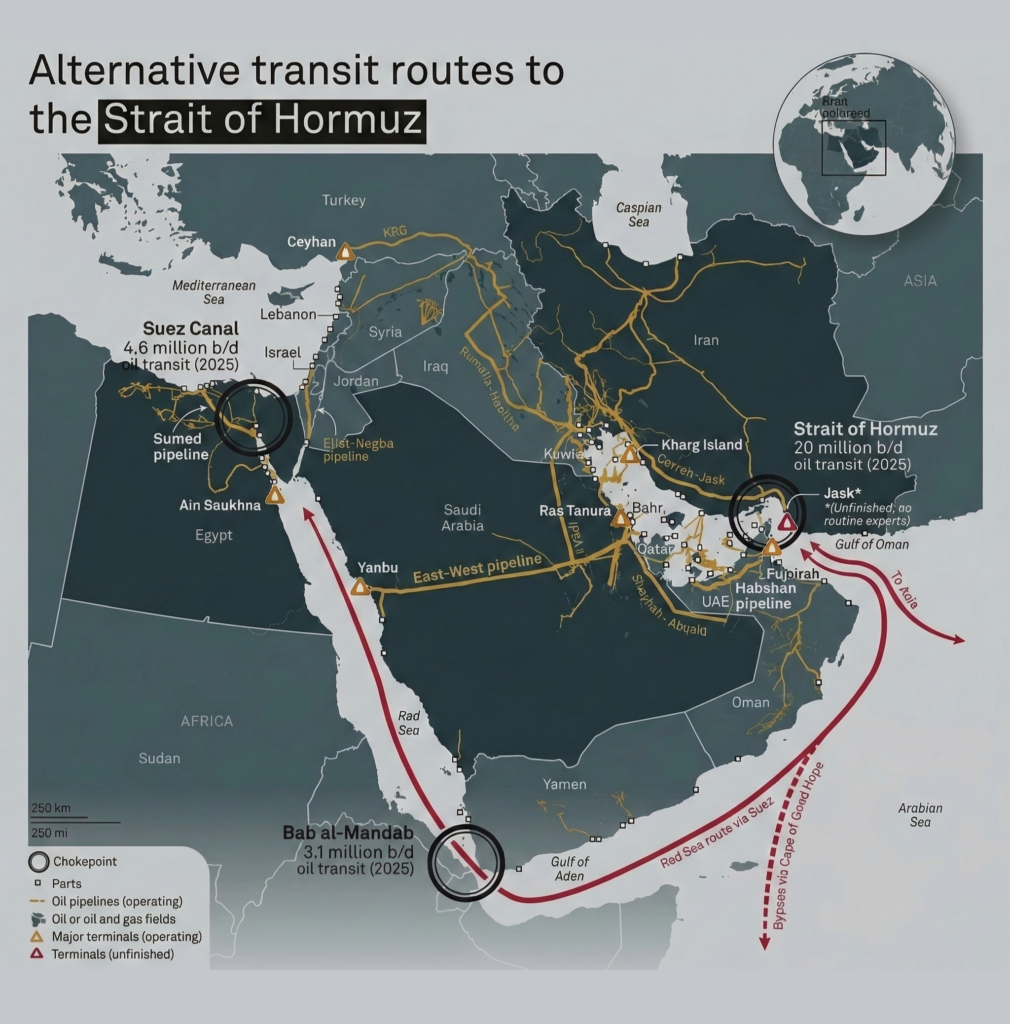
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
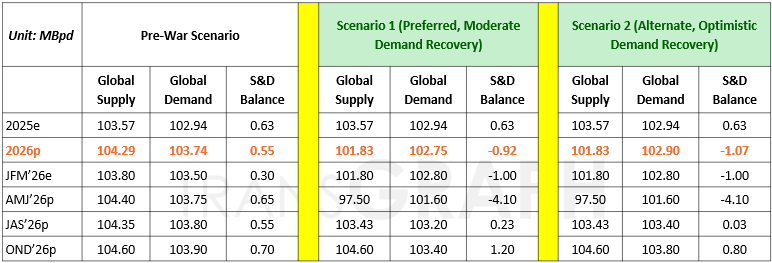
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
War Front: Escalation Spreads to Saudi Arabia and Red Sea.
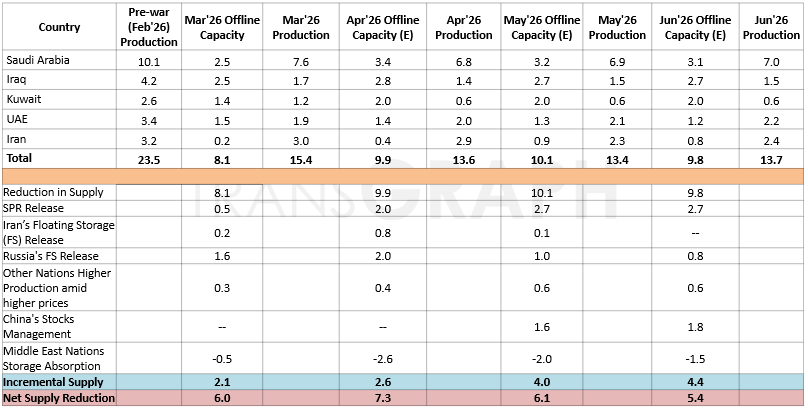
The war continued to widen as Houthi attacks on Saudi Arabia triggered further Saudi airstrikes in Yemen and expanded security alerts across the kingdom, including near Mecca, while shipping through the Strait of Hormuz fell to just four vessels on Tuesday. The disruption to Hormuz and Saudi oil infrastructure is keeping energy markets tight, with Brent above USD 107/bbl, increasing geopolitical risk premiums and raising energy and logistics risks for GCC aluminum smelters. although crude oil prices eased on Wednesday after a larger-than-expected build in U.S. crude inventories.
The U.S Federal Reserve raised its benchmark interest rate by 25 bps to 3.75%-4.00%, marking its first rate hike since July 2023. The decision came amid persistent inflationary pressures, with the Fed stating that inflation remains elevated and that the latest rate increase would support a more timely return toward its 2% inflation target. The Fed’s updated projections indicate that 16 of 18 policymakers expect at least one more 25-bps rate hike by the end of 2026, taking the policy rate to 4.00%-4.25%. Policymakers also raised their 2026 inflation forecast, reflecting continued concerns over price pressures, particularly from higher energy costs. The Fed’s hawkish stance provides a positive backdrop for the USD and weigh on metal prices. This may keep the impact on INR relatively contained, with oil prices, capital flows and RBI intervention remaining key drivers.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
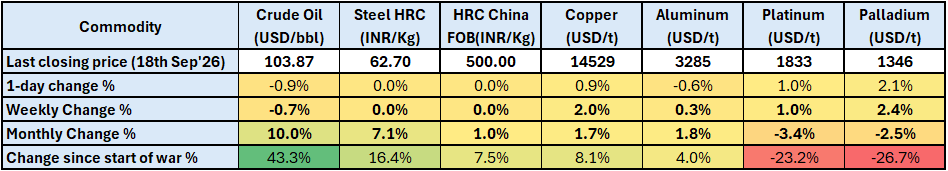
- Moreover, HRC prices are up by 7.1% on a monthly basis due to raw material price surge.
Base metals:
- LME 3M copper are up 2% on a weekly basis supported by high China premium, and drawdown in SHFE inventory. However upside remains capped by rate hike pressures, tariff clarity, and geopolitical tensions.
- Aluminum prices are up 0.3% due to renewed tensions supporting energy prices and risk premium. However, gradual recovery from GCC and rate hike expectations will cap any significant upside.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For August 2026, Saudi Aramco Contract Prices (CPs) rebounded to USD 620/ton for propane and USD 640/ton for butane, compared with USD 580/ton and USD 600/ton, respectively, in July. This represents a 6.9% month-on-month increase in propane CPs and a 6.7% month-on-month increase in butane CPs.
- Sonatrach raised its August propane OSP by 4.2% m-o-m, from $518/ton to $540/ton, while the butane OSP was cut by 5.0%, from $600/ton to $570/ton.
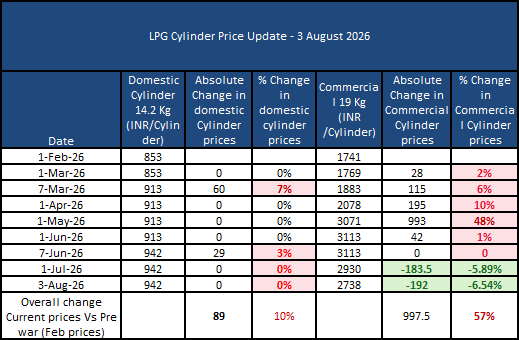
- India’s commercial LPG prices eased further in August, with the 19 kg cylinder price in New Delhi declining by ₹192, from ₹2,930 in July to ₹2,738 as of 3 August 2026. Despite the recent correction, commercial LPG remains substantially above its pre-war level of ₹1,741/cylinder. In contrast, the 14.2 kg domestic LPG cylinder remained unchanged at ₹942, reflecting continued price stability for household consumers.