- The latest escalation came after Houthi militants seized control of Yemen’s port city of Mocha and increased attacks around the Bab el-Mandeb Strait, creating an additional threat to crude and refined-product flows through the Red Sea, while continued disruption in the Strait of Hormuz further tightened supply concerns, with only seven vessels transiting the strait on 09th Sep’26, around half of the 10-day average.
- The risk to Saudi Arabian oil exports has also increased, as Houthi attacks could disrupt the Red Sea route that Saudi Arabia is increasingly relying on to bypass Hormuz.
- Meanwhile, the US President Trump said he expects the US–Iran war to end immediately after the midterm elections and indicated that oil prices would decline following the end of the conflict, although the immediate market reaction remains bullish as renewed attacks continue to threaten regional supply and shipping flows.
- Vessel traffic through the Strait of Hormuz fell to seven on 10th Sep’26 from 11 the previous day, well below the 10-day average of 15, while 26 commodity vessels transited the Bab el-Mandeb Strait versus a 10-day average of 27, highlighting continued disruption in Hormuz despite the first Qatar-linked LNG shipment since late Jul’26.
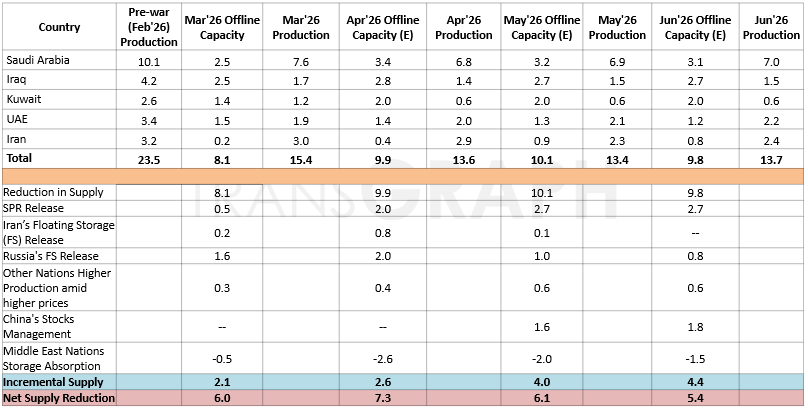
- China’s seaborne crude oil imports increased marginally to 7.14 MBpd in Aug’26 from 6.93 MBpd in Jul’26, but remained 4.27 MBpd (37%) below the pre-conflict average of 11.41 MBpd, as constrained Middle East flows and elevated crude prices continued to limit imports.
- Meanwhile, China increased seaborne crude imports from Russia to 1.68 MBpd in Aug’26 from 1.40 MBpd in Jul’26, while light and middle distillate exports rose to 0.96 MBpd from 0.77 MBpd, suggesting that higher refinery product exports could support further crude imports if Asian product margins remain elevated..
- The US national average diesel price surpassed 6 USD/gal for the first time on 11th Sep’26, driven by supply disruptions from the US–Iran conflict and attacks on Russian refineries, increasing transportation, freight, agricultural, and logistics costs and thereby adding further inflationary pressure across the US economy, particularly as higher operating and delivery costs are passed through to consumers and businesses.
- Market grapevine indicates that the global diesel markets are expected to remain tight as disruptions have removed nearly 2.00 MBpd of Russian and 2.00 MBpd of Middle Eastern product supplies, while limited spare refining capacity and approaching winter demand are supporting record high diesel margins, with US diesel crack spreads reaching 108.02 USD/bbl.
- Rosneft’s Ryazan refinery halted operations following a 06th Sep’26 drone attack, with its CDU-6 unit (160 kbpd production capacity) and CDU-4 unit (80 kbpd production capacity) taken offline, while CDU-3 remains under maintenance, potentially affecting around 240 kbpd of crude-processing capacity.
- The refinery processed approximately 13.1 mln tons (96 mln bbl) of crude in 2024, representing about 4.9% of Russia’s total refining throughput, and produced 2.2 mln tons (16.1 mln bbl) of gasoline, 3.4 mln tons (24.9 mln bbl) of diesel, and 4.3 mln tons (31.5 mln bbl) of fuel oil.
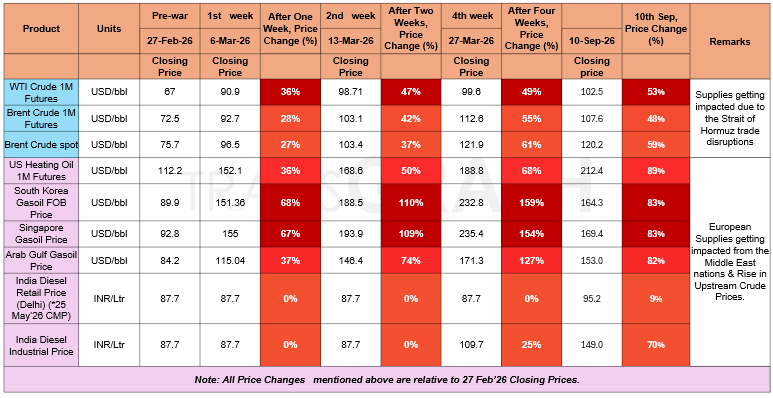
War Impact on Crude Oil & Gasoil/Diesel Prices
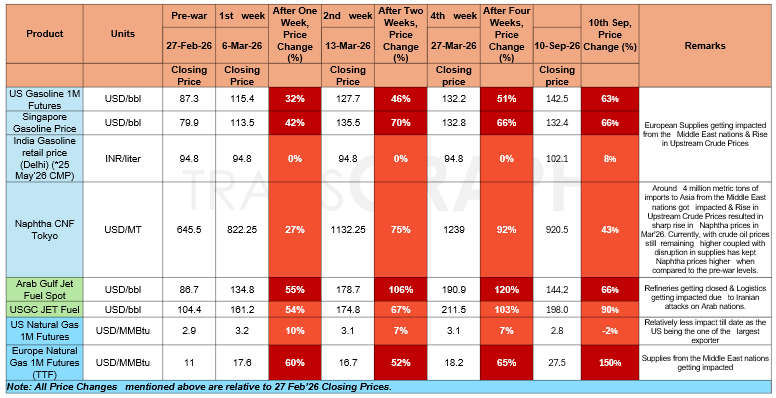
War Impact on Gasoline, ATF & Natural Gas Prices
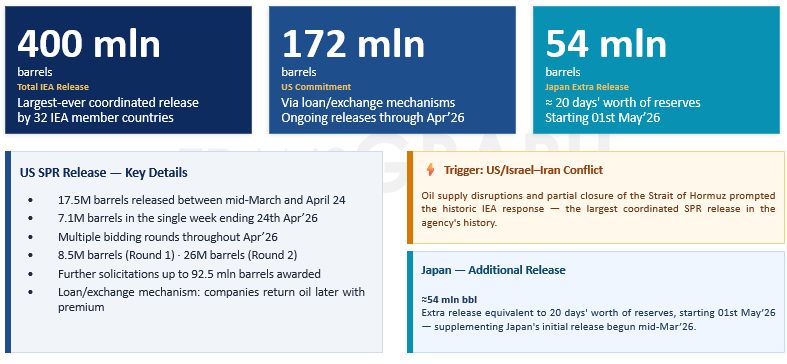
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
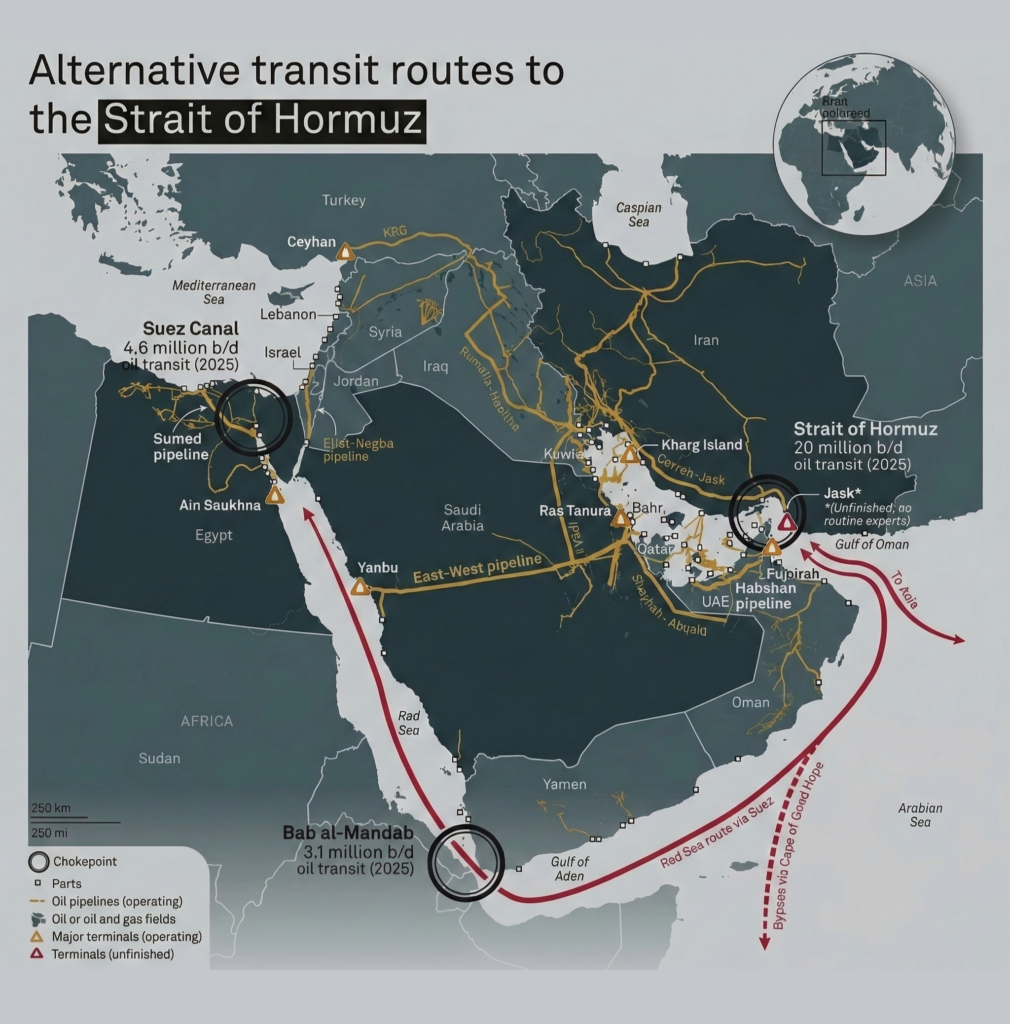
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
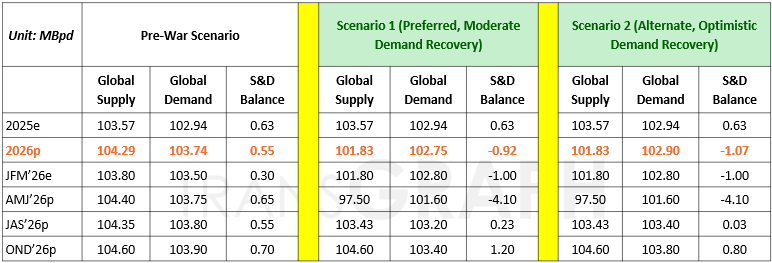
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
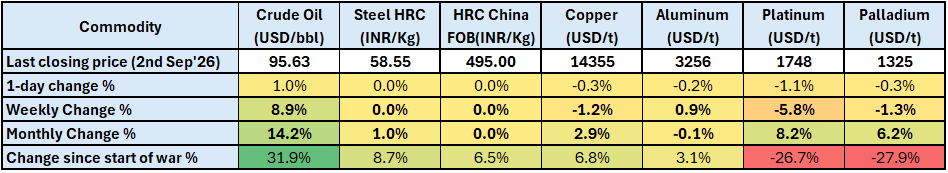
US-Iran Hostilities Reignite, Raising Hormuz Risk: U.S.-Iran tensions remain elevated following renewed military exchanges. U.S. Central Command said Tuesday it had completed a new wave of attacks against Islamic Revolutionary Guard Corps targets, including air defense sites, radar systems and communications sites. Iranian state media said the strikes killed 18 people and injured 108, citing the country's health minister, and added that Iran retaliated by hitting Camp Titin, a U.S. Marine base in Jordan, with ballistic missiles. The renewed conflict has pushed Brent crude oil above USD 95/bbl, as concerns over potential supply disruptions and reduced shipping activity through the Strait of Hormuz added a significant geopolitical risk premium to energy markets.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 1% on a monthly basis due to raw material price surge.
Base metals:
- Copper prices are down 1.2% on a weekly basis as Kevin Warsh's Jackson Hole speech renewed rate hike expectations citing inflationary concerns. Further, escalation in the Gulf, weak Chinese economic data, and inventory buildup is weighing on market sentiments. However, downside remains capped due to supply tightness, CME-LME spread, backwardation structure, and lowered production guidance in Chile.
- Aluminum prices are up 0.9% on a weekly basis due to renewed tensions in West Asia.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For August 2026, Saudi Aramco Contract Prices (CPs) rebounded to USD 620/ton for propane and USD 640/ton for butane, compared with USD 580/ton and USD 600/ton, respectively, in July. This represents a 6.9% month-on-month increase in propane CPs and a 6.7% month-on-month increase in butane CPs.
- Sonatrach raised its August propane OSP by 4.2% m-o-m, from $518/ton to $540/ton, while the butane OSP was cut by 5.0%, from $600/ton to $570/ton.
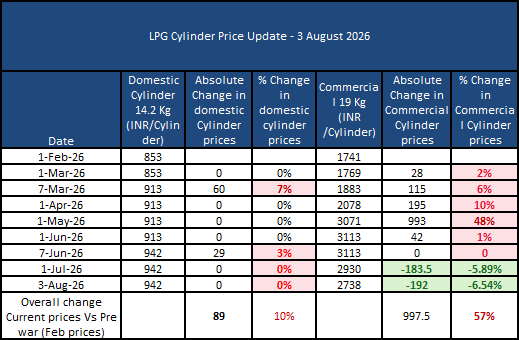
- India’s commercial LPG prices eased further in August, with the 19 kg cylinder price in New Delhi declining by ₹192, from ₹2,930 in July to ₹2,738 as of 3 August 2026. Despite the recent correction, commercial LPG remains substantially above its pre-war level of ₹1,741/cylinder. In contrast, the 14.2 kg domestic LPG cylinder remained unchanged at ₹942, reflecting continued price stability for household consumers.