- OPEC+ members agreed to keep Dec’26 oil production targets unchanged, as ongoing Iran war-related disruptions continue to limit Gulf exports, with most producers pumping below their agreed targets.
- The group is expected to decide its 2027 production policy at the 29th Nov’26 meeting, balancing uncertainty over the recovery of Middle East supplies against the risk of a global oil surplus next year.
- Updated tracking of Middle Eastern Gulf and Gulf of Oman petroleum exports showed a sharp provisional decline in the seven-day average following the reported recovery toward prewar levels. However, tanker tracking firms explicitly warns that its latest 14 days of observations are subject to upward revision as shipments are confirmed.
- Asia’s crude oil imports recovered to 26.39 MBpd in Oct’26, up from 24.24 MBpd in Sep’26 and close to the pre-conflict average of 27.0 MBpd, supported by improved Middle Eastern shipments through the Strait of Hormuz.
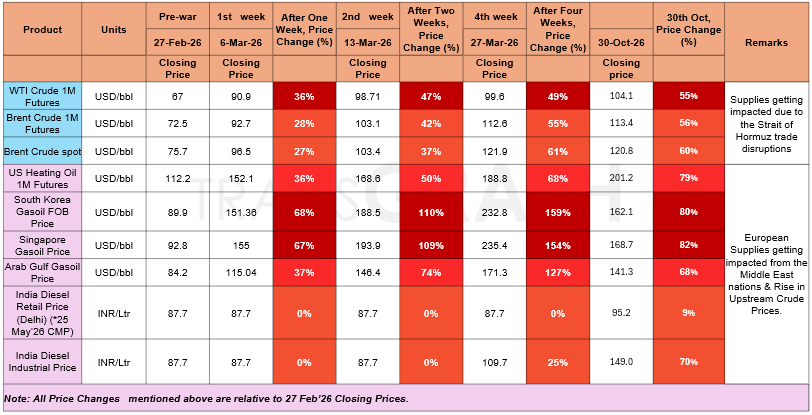
- However, refined fuel imports remained 10% below pre-war levels at 6.15 MBpd, while Singapore gasoil prices stood at 168.62 USD/bbl (84% above pre-war levels), highlighting continued tightness in diesel and refined product markets.
- Freight rates for Russian Urals crude shipments to India surged to around 30 USD/bbl or higher in late Oct’26, up from approximately 20 USD/bbl in Sep’26, driven by Black Sea security risks, tanker shortages and strong shipping demand, significantly increasing export costs for Russian oil sellers.
War Impact on Crude Oil & Gasoil/Diesel Prices
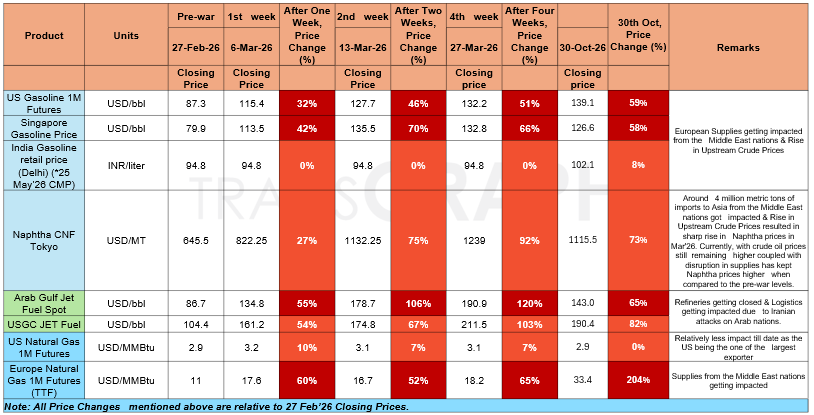
War Impact on Gasoline, ATF & Natural Gas Prices
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
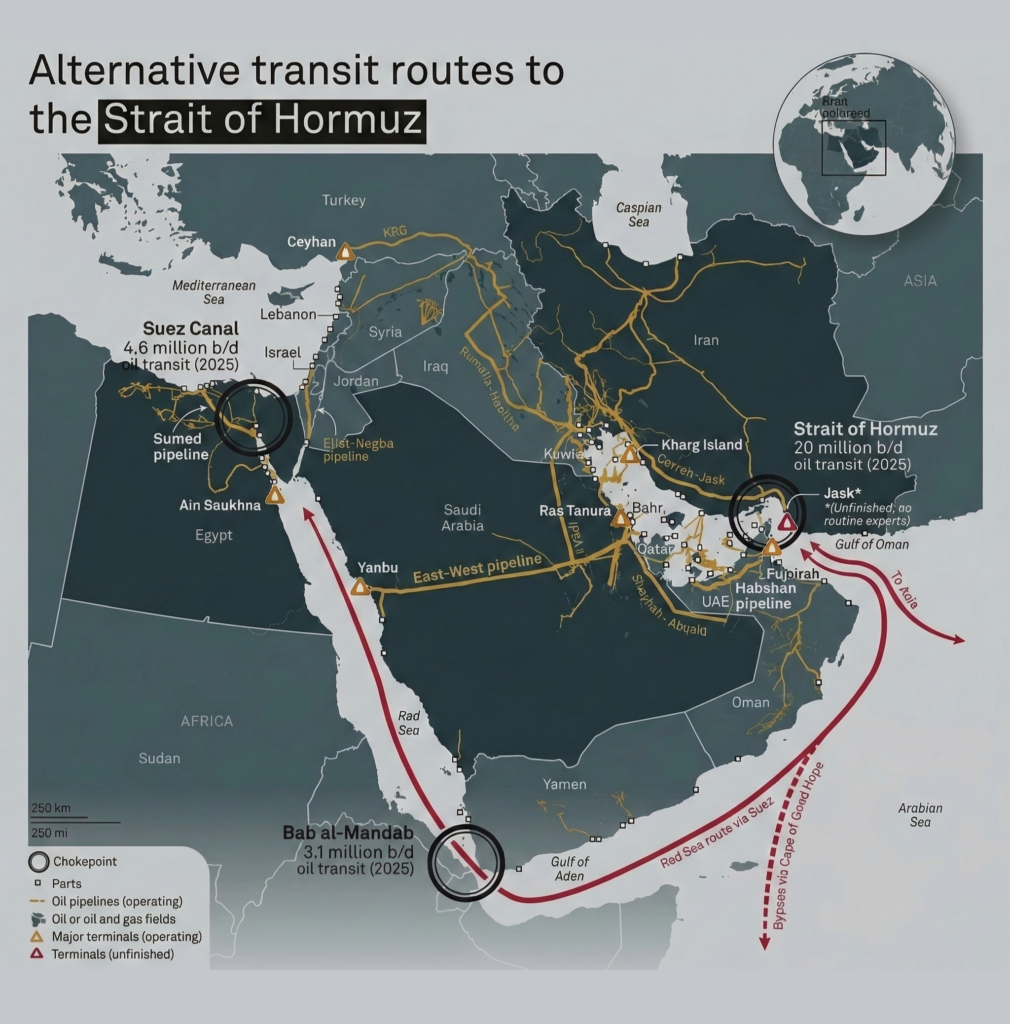
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
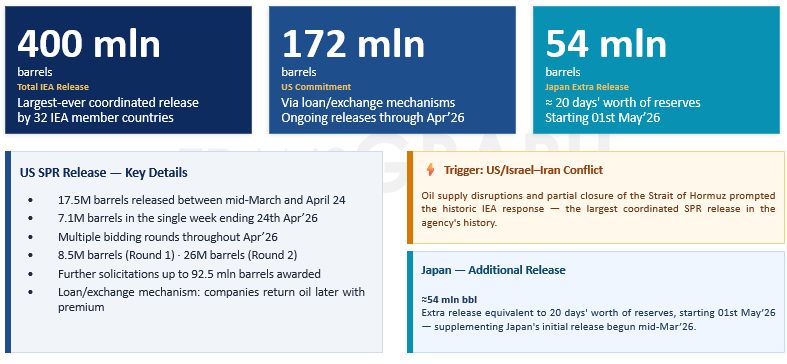
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
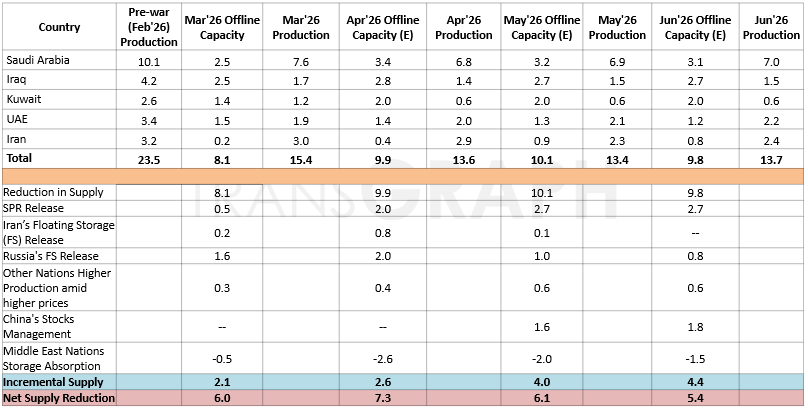
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
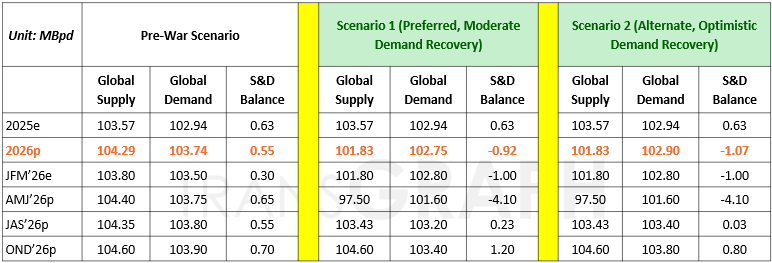
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
War Front: U.S.-Iran tensions remain elevated despite renewed diplomatic efforts to prevent further escalation. Iran has proposed a seven-day plan to reopen the Strait of Hormuz and remains in contact with mediators, although President Trump has denied reports that formal peace talks are underway. Meanwhile, Houthi attacks have intensified, with Saudi-led coalition forces reporting the interception of a ballistic missile aimed at Saudi Arabia and a fresh attack on Yemen’s Aden airport disrupting air traffic. Looking ahead, developments following the 3 November U.S. midterm elections could provide greater clarity on the direction of the conflict.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
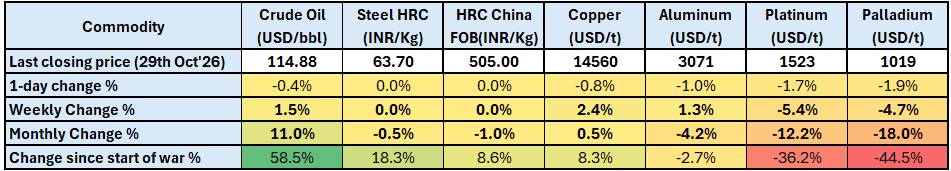
- Moreover, HRC prices are up down 0.5% on a monthly basis as weaker trading activity during festive season capped support from raw material price surge.
Base metals:
- LME 3M copper are up by 2.4% on a weekly basis as Fed holds interest rates. Further, high China premium, supply disruptions, and backwardation structure is supporting prices. However, significant upside remains capped by pressure from higher CPI reading and geopolitical tensions,
- Aluminum prices are up 1.3% on a weekly basis due to renewed tensions in West Asia capping pressure from recovery in GCC production.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For October, Saudi Aramco CP was set at USD 680/ton for propane and USD 730/ton for butane, representing increases of USD 55/ton and USD 70/ton, respectively, from September levels. The propane-butane spread widened further to USD 50/ton, compared with USD 35/ton in September and USD 20/ton in August, indicating continued relative strength in butane pricing and tighter butane availability compared with propane. The larger month-on-month increase in butane also points to a stronger rise in butane market tightness entering October.
- Sonatrach increased its October propane OSP by USD 110/ton, from USD 560/ton in September to USD 670/ton. Meanwhile, the butane OSP increased by USD 140/ton, from USD 610/ton to USD 750/ton.
- US LPG prices strengthened across the board between 1 October and 8 October 2026, with propane rising by 8.6% to USD 466/ton from USD 429/ton. Butane increased by 7.6% to USD 738/ton from USD 686/ton, while the 50:50 LPG blend climbed by 8.0% to USD 601.77/ton from USD 557.28/ton. Notably, the Mont Belvieu 50:50 LPG blend crossed the USD 600/ton threshold for the first time since 2022, underscoring the strength of the current price rally. The simultaneous increase in propane and butane indicates broad-based upward pressure across the US LPG market rather than a rally driven by a single component.