- Yemen’s Houthi group claimed to have struck Saudi Arabia’s Ras Tanura refinery, which has a processing capacity of approximately 0.55 MBpd with a ballistic missile on 27th Oct’26 reportedly causing a fire at the refinery and adjacent oil export terminal.
- Saudi Arabia, Turkey and Pakistan held talks with Iranian officials on 26th Oct’26 in Tehran to de escalate regional tensions, with Iran describing the discussions as positive and all parties agreeing to continue dialogue.
- Saudi Aramco plans to double its overseas crude oil storage capacity, particularly in Asia, to strengthen supply security amid regional disruptions, with Saudi Arabia and Singapore announcing plans on 26th Oct’26 to store Saudi crude at Singapore’s Jurong Rock Caverns where operations are expected to begin in the second half of 2027.
- OPEC+ is expected to maintain its Dec’26 crude oil production targets at its scheduled meeting on 1st Nov’26. The 7 core members- Saudi Arabia, Russia, Iraq, Kuwait, Algeria, Kazakhstan and Oman are reviewing production arrangements with most continuing to produce below their assigned targets, while preparations are underway to establish production baselines and quotas for 2027.
- Russia and Ukraine began a temporary ceasefire around Russian occupied Oleshky in the Kherson region to facilitate humanitarian aid deliveries and civilian evacuations, including the supply of food, medicine and water to residents facing shortages, with the truce expected to continue until 31st Oct’26.
- Russian seaborne crude exports from Baltic and Black Sea ports including Kazakh crude transported through Russia are expected to decline by approximately 0.1-0.2 MBpd in Nov’26 compared with Oct’26, driven by higher refinery processing following maintenance, increased domestic diesel production under the US-Russia fuel agreement and ongoing shipping disruptions in the Black Sea.
- Commercial shipping attacks in the Strait of Hormuz and surrounding waterways reached a monthly record in Oct’26, with 28 reported attacks as of 23 Oct’26 and 113 cumulatively since 28th Feb’26. More than 30 very large crude carriers (VLCCs) had reportedly been damaged since the conflict began, including 11 in Oct’26, while 12 ships were attacked between 5th and 11th Oct’26, marking the highest weekly total since the conflict began and increasing risks to crude oil shipments through the strategic waterway.
- US Strategic Petroleum Reserve (SPR) crude inventories declined to 282.6 mln bbl, their lowest level since Oct 1982, amid the government’s planned release of 172 mln bbl. Meanwhile, the US Department of Energy authorised an emergency exchange of up to 0.4 mln bbl of crude oil to address a supply disruption affecting Phillips 66’s Lake Charles refinery in Louisiana.
- Two tankers carrying 1.0 mln bbl of Venezuelan crude arrived at Corpus Christi, Texas for ExxonMobil and Citgo refineries under a US-North American Blue Energy Partners (NABEP) agreement which grants Washington rights to purchase 20% of NABEP’s production at cost and a 35% stake in its parent company.
- US President Donald Trump stated that Washington would not launch an attack on Iran before the 3rd Nov’26 midterm elections, citing ongoing productive discussions with Tehran aimed at resolving the conflict.
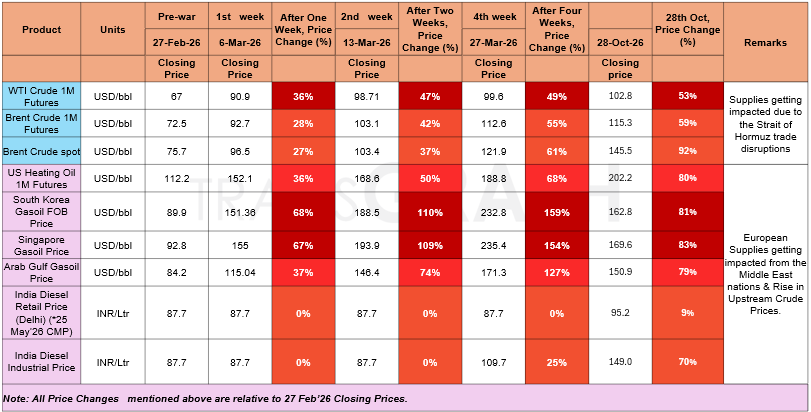
War Impact on Crude Oil & Gasoil/Diesel Prices
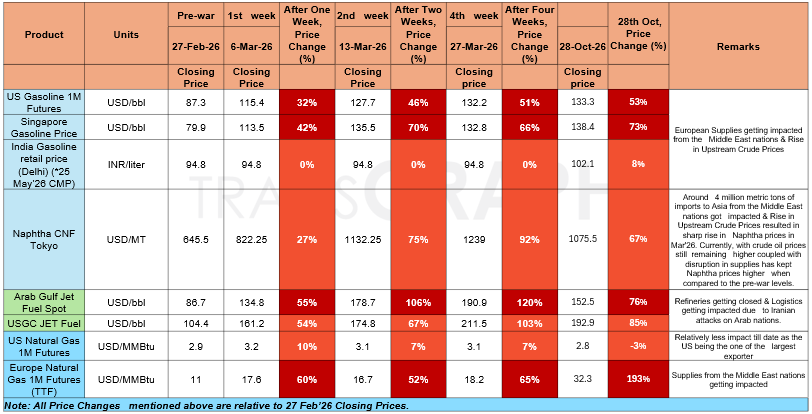
War Impact on Gasoline, ATF & Natural Gas Prices
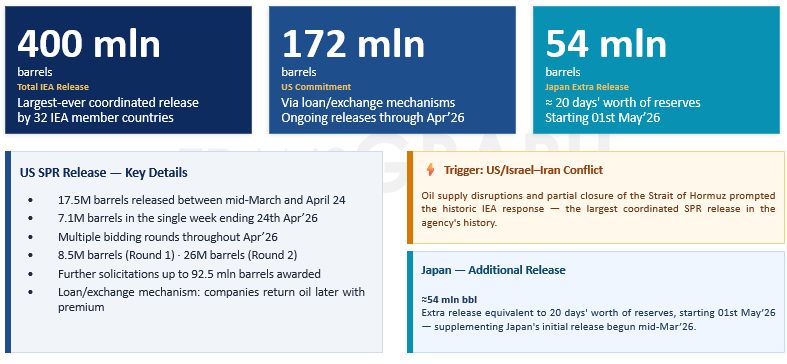
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
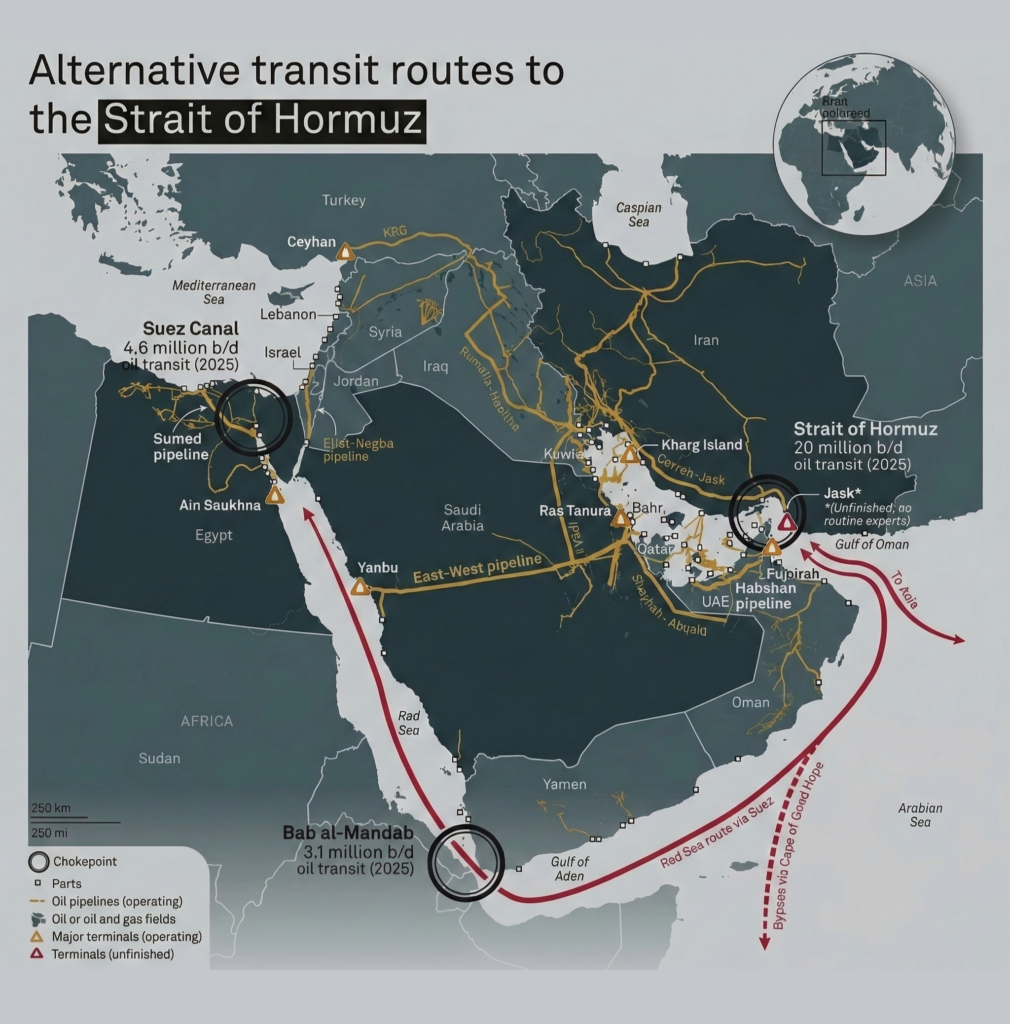
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
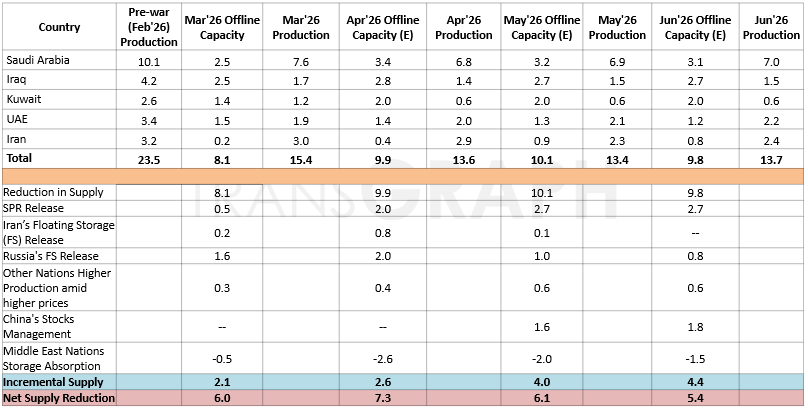
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
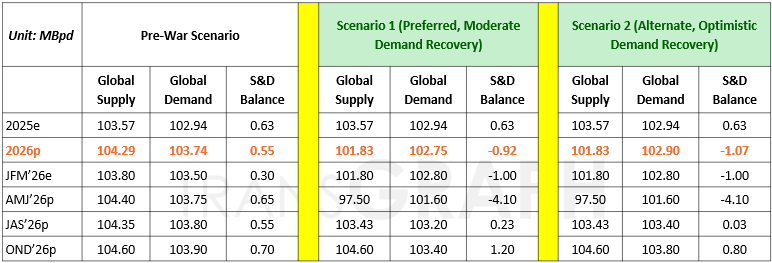
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
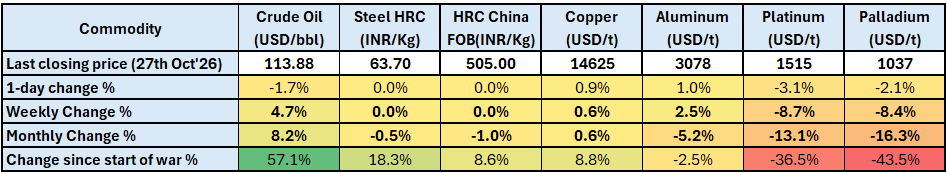
War Front: U.S.-Iran tensions remained elevated as renewed Houthi attacks on Saudi Arabia heightened regional security risks. However, Brent crude futures fell 1.7% on Tuesday, settling at USD 113.88/barrel, as renewed diplomatic engagement involving Iran, Saudi Arabia, Pakistan and Turkey eased some concerns over potential supply disruptions. Despite the decline, oil prices remained near six-month highs, reflecting continued risks to Gulf energy infrastructure and shipping routes. Looking ahead, developments following the 3 November U.S. midterm elections could provide greater clarity on the direction of the conflict. A lack of renewed strikes on Iran could be sufficient to gradually erode the geopolitical risk premium, even without a comprehensive agreement.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up down 0.5% on a monthly basis as weaker trading activity during festive season capped support from raw material price surge.
Base metals:
- LME 3M copper are up by 0.6% on a weekly basis as reduced rate hike expectations, high China premium, supply disruptions, and backwardation structure. capped pressure from higher CPI reading and geopolitical tensions,
- Aluminum prices are up 2.5% on a weekly basis due to renewed tensions in West Asia capping pressure from recovery in GCC production.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For October, Saudi Aramco CP was set at USD 680/ton for propane and USD 730/ton for butane, representing increases of USD 55/ton and USD 70/ton, respectively, from September levels. The propane-butane spread widened further to USD 50/ton, compared with USD 35/ton in September and USD 20/ton in August, indicating continued relative strength in butane pricing and tighter butane availability compared with propane. The larger month-on-month increase in butane also points to a stronger rise in butane market tightness entering October.
- Sonatrach increased its October propane OSP by USD 110/ton, from USD 560/ton in September to USD 670/ton. Meanwhile, the butane OSP increased by USD 140/ton, from USD 610/ton to USD 750/ton.
- US LPG prices strengthened across the board between 1 October and 8 October 2026, with propane rising by 8.6% to USD 466/ton from USD 429/ton. Butane increased by 7.6% to USD 738/ton from USD 686/ton, while the 50:50 LPG blend climbed by 8.0% to USD 601.77/ton from USD 557.28/ton. Notably, the Mont Belvieu 50:50 LPG blend crossed the USD 600/ton threshold for the first time since 2022, underscoring the strength of the current price rally. The simultaneous increase in propane and butane indicates broad-based upward pressure across the US LPG market rather than a rally driven by a single component.