- The IEA lowered its global oil demand outlook, projecting a decline of 2.6 mln barrels per day (mb/d) in 2026, with demand expected to fall by 2.5 mb/d year-on-year in Q4’26. High fuel prices, supply constraints and a deteriorating economic outlook are weighing on consumption, with diesel accounting for approximately 25% of the projected annual decline.
- Despite the weaker demand outlook, global oil supply risks remain elevated. The IEA reported that global oil supply increased by 2.5 mb/d month-on-month to 102.3 mb/d in Sep’26, driven by higher output from Gulf producers; however, renewed attacks on energy infrastructure and shipping routes threaten to disrupt the recovery in regional exports and sustain volatility in crude oil prices.
- Crude oil transportation costs from the US to Japan surged to USD 81 mln for a 2 mln-barrel cargo (USD 40.50/bbl) in late Nov’26, nearly nine times the average cost of USD 9.1 mln last year, with freight accounting for over 40% of US crude prices compared with 7% in 2025.
- Tanker freight rates from the Strait of Hormuz and the Red Sea to Asia reached a record USD 34/bbl amid US-Iran and Russia-Ukraine war-related attacks, elevated insurance premiums and longer shipping routes, tightening vessel availability and increasing crude procurement costs for import-dependent countries such as India, while further squeezing Asian refiners’ margins.
- The Trump administration is considering easing sanctions on shadow fleet vessels to increase the flow of crude oil and petroleum products from the Gulf and help reduce record-high global tanker freight rates, which have made US crude less competitive for Asian refiners.
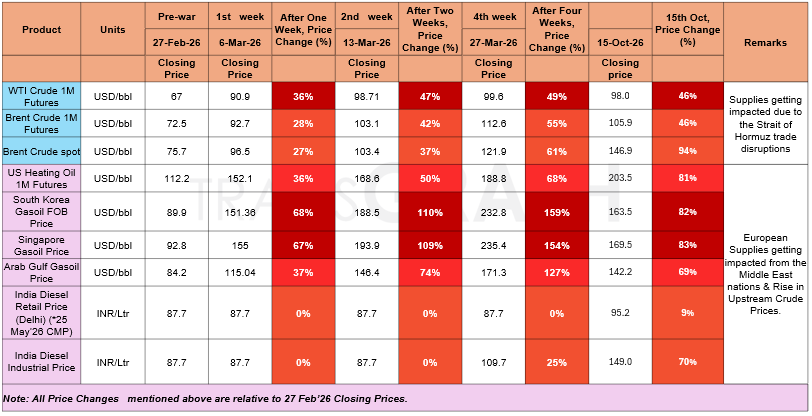
War Impact on Crude Oil & Gasoil/Diesel Prices
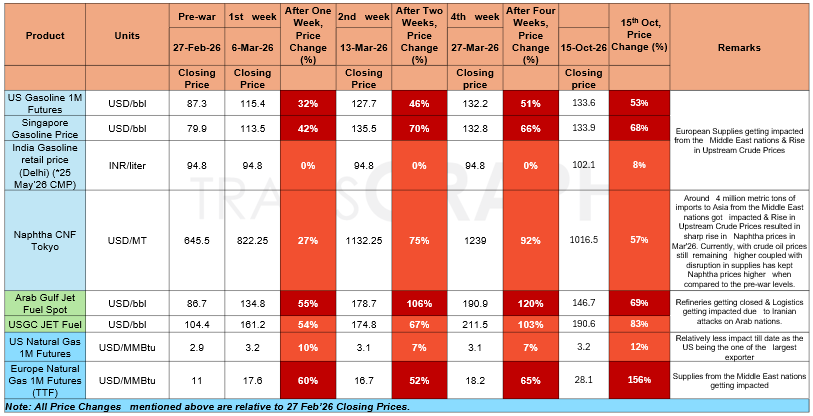
War Impact on Gasoline, ATF & Natural Gas Prices
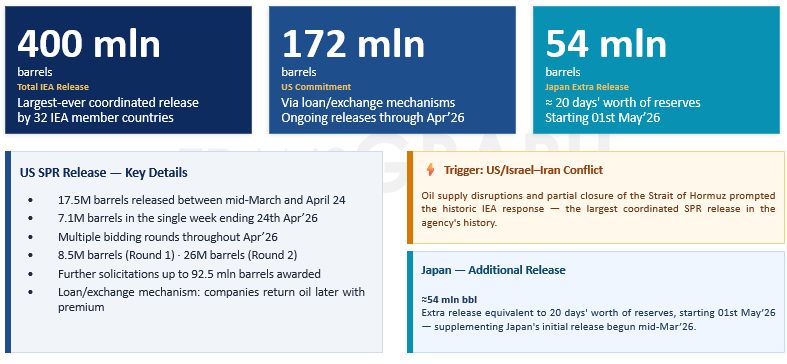
GCC Bypass Pipelines Running Near Capacity — But Shah Gas Field Ablaze and Fujairah Zone Struck
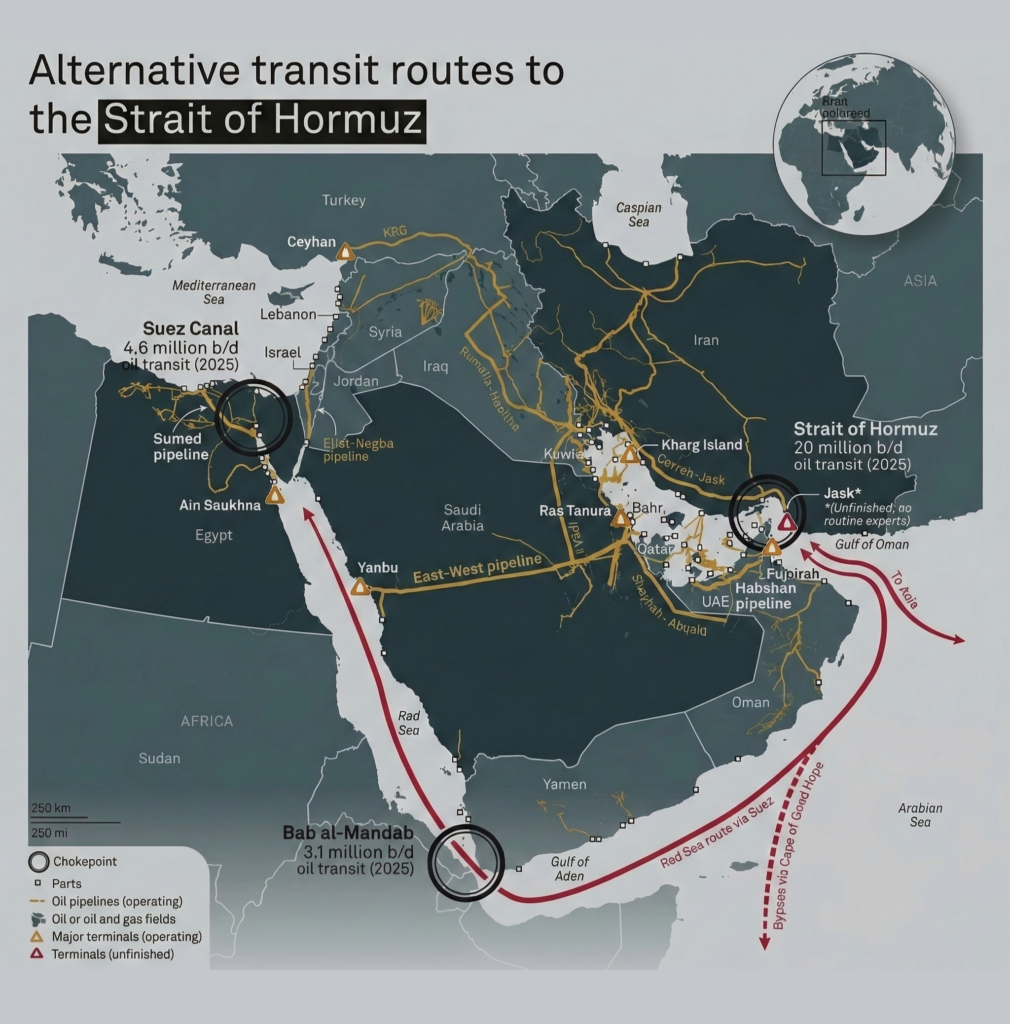
- Saudi Arabia's East-West pipeline is pumping oil at its full capacity of 7 MBpd, bypassing the Strait of Hormuz. Crude oil exports from Yanbu port have reached 5 MBpd, and the country is also exporting 0.70 to 0.90 MBpd of oil products.
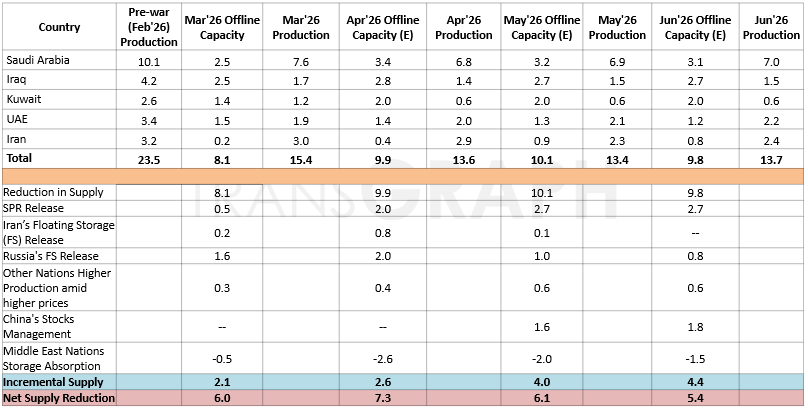
- Of approximately 15 MBpd of crude transiting the Strait of Hormuz in OND'25, combined SPR releases and bypass pipeline capacity can offset roughly two-thirds — or slightly more — for the next 20 to 30 days, providing the Trump administration a window to assess strategic direction.
- New strikes directly threaten this buffer — Iranian drones struck the UAE's Shah gas field (currently ablaze) and the Fujairah Oil Industry Zone on Mar 17. A tanker was also hit near the Strait of Hormuz. Saudi Arabia intercepted over a dozen drones; Kuwait and Bahrain sustained additional attacks. These represent the first direct strikes on GCC energy export infrastructure since the conflict began.
War Scenarios Point to Global Supply Deficit of 0.92–1.07 MBpd in 2026 and AMJ Quarter Most Severe with a deficit of 4.10 MBpd.
Pre-war, global supply and demand were near-balanced with a modest surplus of +0.55 MBpd projected for 2026. Both conflict scenarios introduce significant supply deficits driven by Strait of Hormuz disruptions and impacts on Iraq and Kuwait crude production.
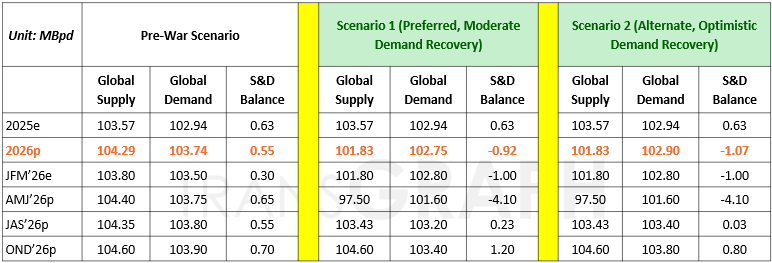
- Scenario 1 (Preferred): Ceasefire talks continue to progress positively, with tanker flows through the Strait of Hormuz gradually normalizing over the next 4–5 weeks. Supply recovers steadily, while demand improves at a slower pace and remains below pre-war expectations, resulting in a moderate market surplus.
- Scenario 2 (Alternate): The Strait of Hormuz normalizes over the next 4–5 weeks, supporting a gradual recovery in oil exports and supply. Demand rebounds more strongly than in Scenario 1, reducing the market surplus, although overall consumption remains below pre-war levels.
Geopolitical backdrop:
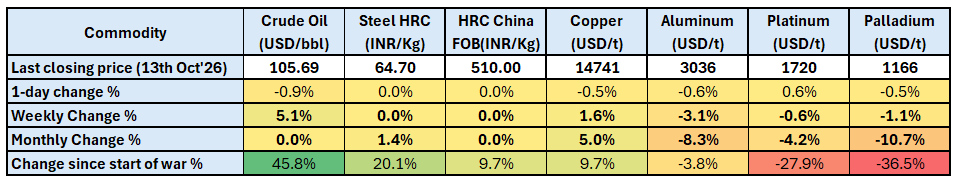
War Front: Middle East tensions escalated as Houthi attacks on Saudi Arabia continued, while Iran intensified disruptions to commercial shipping around the Strait of Hormuz, with at least five maritime incidents reported within 48 hours. Brent crude rose 0.8% to USD 106.58/barrel amid renewed Gulf supply concerns.
US central bank viewed inflation as the biggest risk to their outlook, with most participants assessed that another increase in the fed funds target range would likely be appropriate by year end. This led to a higher Treasury yields ,strengthening the dollar’s interest rate differentials. However, September nonfarm payrolls increased by only 29K, well below expectations, adding to expectations that the Fed may have less scope for October Fed rate hike, along with dovish comments from New York Fed President John Williams, further limited the dollar’s upside.
Steel:
- Steel supply chains remain largely insulated from the Middle East conflict.
- Moreover, HRC prices are up by 1.4% on a monthly basis due to raw material price surge and stronger demand from auto sector.
Base metals:
- LME 3M copper are up by 1.6% on a weekly basis as support from weaker job data, reduced rate hike expectations, several supply disruptions in Chile (Escondida, Radomiro Tomic, and Centinela), backwardation structure was capped by progress in Grasberg repairs and geopolitical tensions.
- Aluminum prices are down 3.1% due to gradual recovery from GCC and stronger dollar despite tensions in the middle east.
Precious metals:
- Stronger U.S. yields and weak industrial offtake are suppressing any upside momentum.
- Stronger US Dollar and geopolitical tensions are weighing on precious metal prices.
LPG Market Update
- For October, Saudi Aramco CP was set at USD 680/ton for propane and USD 730/ton for butane, representing increases of USD 55/ton and USD 70/ton, respectively, from September levels. The propane-butane spread widened further to USD 50/ton, compared with USD 35/ton in September and USD 20/ton in August, indicating continued relative strength in butane pricing and tighter butane availability compared with propane. The larger month-on-month increase in butane also points to a stronger rise in butane market tightness entering October.
- Sonatrach increased its October propane OSP by USD 110/ton, from USD 560/ton in September to USD 670/ton. Meanwhile, the butane OSP increased by USD 140/ton, from USD 610/ton to USD 750/ton.
- US LPG prices strengthened across the board between 1 October and 8 October 2026, with propane rising by 8.6% to USD 466/ton from USD 429/ton. Butane increased by 7.6% to USD 738/ton from USD 686/ton, while the 50:50 LPG blend climbed by 8.0% to USD 601.77/ton from USD 557.28/ton. Notably, the Mont Belvieu 50:50 LPG blend crossed the USD 600/ton threshold for the first time since 2022, underscoring the strength of the current price rally. The simultaneous increase in propane and butane indicates broad-based upward pressure across the US LPG market rather than a rally driven by a single component.